

Blogs
PW Consulting Reports Worldwide High-Resolution Mass Spectrometry Market to Reach $4.9B by 2032, CAGR 8.12%
By PW Consulting, 2026-09-17
Navigating the High-Resolution Mass Spectrometry Landscape: Strategic Intelligence for 2026 and Beyond
The global landscape for analytical instrumentation is undergoing a definitive transformation, driven by the converging demands of precision medicine, stringent environmental regulations, and advanced proteomics research. For executive leadership and strategic planners, understanding the trajectory of the Worldwide High Resolution Mass Spectrometry System Market is no longer optional—it is a critical component of capital allocation and R&D roadmap planning. As we move through 2026, the market presents a complex mix of robust growth opportunities and regulatory hurdles that require nuanced interpretation.
PW Consulting has released a comprehensive market research study designed to cut through the noise and provide actionable intelligence. This document serves as an introduction to that findings pack, outlining the strategic value contained within the full report while highlighting the macro trends shaping the industry through 2032.
Market Trajectory and Growth Signals
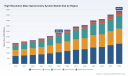
The historical performance of the high-resolution mass spectrometry (HRMS) sector indicates a resilient upward trend. Between 2020 and 2025, the market expanded from approximately 1935.2 million USD to 2851.32 million USD. This growth trajectory is projected to continue, with revenue expectations reaching 3163.87 million USD in 2026 and climbing to 4924.8 million USD by 2032.
Our analysis projects a Compound Annual Growth Rate (CAGR) of 8.12 percent over the forecast period from 2026 to 2032. This sustained expansion reflects the increasing reliance on HRMS technologies for complex molecular characterization. The base year for this analysis is 2025, ensuring that the forecast models account for the most recent economic shifts and supply chain stabilizations observed in the late 2020s.
Stable Isotope Ratio Mass Spectrometer Market
Decoding the Competitive Landscape
The market environment is characterized by significant concentration among key players, yet innovation remains highly dispersed across different technological architectures. The top three companies command a market concentration of 58.42 percent, while the top five hold 76.15 percent. This structure suggests a mature market where scale matters, but niche innovation can still disrupt specific application verticals.
Thermo Fisher Scientific continues to anchor the market with its extensive Orbitrap high-resolution accurate mass (HRAM) systems. Recent developments include the launch of the Orbitrap Astral Zoom and Orbitrap Excedion Pro in June 2025. These systems are designed to enhance speed and sensitivity for precision medicine and proteomics. Furthermore, their LC-MS medical devices, such as the TSQ Altis MD and Quantis MD series, bridge the gap between research and clinical laboratory settings, although these are currently intended as components in laboratory-developed tests rather than standalone IVD instruments.
Worldwide High Resolution Mass Spectrometry System Market
Waters Corporation has strengthened its biopharma and clinical research position with the Xevo TQ Absolute XR Mass Spectrometer. Launched at ASMS 2025, this system notably offers reduced power and gas consumption, addressing the operational efficiency demands of high-throughput laboratories.
Agilent Technologies and Bruker Corporation remain pivotal in driving analytical capabilities. Agilent supplies quadrupole time-of-flight (Q-TOF) systems critical for toxicology and clinical research. Meanwhile, Bruker introduced the timsUltra AIP System and timsOmni mass spectrometer in June 2025, focusing on functional proteoform sequencing and peptide identification capabilities that are essential for advanced spatial biology.
Danaher Corporation (SCIEX) has pushed the envelope in high-throughput screening with the ZenoTOF 8600 system. This platform enables rapid analysis of thousands of molecular species in complex biological samples, reinforcing the trend toward speed and depth of coverage in clinical diagnostics.
Shimadzu Corporation and JEOL Ltd. provide integrated solutions often focused on compound identification and laboratory analysis, while Roche represents a unique shift toward routine clinical integration. Roche's CE-marked cobas Mass Spec platform, expanded in December 2025 to include an broad IVD menu of 39 tests, signals a move toward automating mass spectrometry in hospital workflows for therapeutic drug monitoring and steroid hormone testing. PerkinElmer rounds out the competitive field with systems dedicated to clinical research and laboratory applications.
Segmentation Dynamics and Application Drivers
Understanding where the revenue originates is vital for strategic positioning. The market is fragmented across technology types, applications, and regions, each with distinct growth catalysts.
Technological Architectures
The market is divided into several core system types. Time-of-Flight (TOF) Systems and Orbitrap Systems represent the dominant portions of the market share, driven by their versatility in proteomics and complex mixture analysis. FT-ICR Systems maintain a presence in high-end structural biology, while Hybrid Systems offer flexible configurations for varied laboratory needs. The choice between these architectures often depends on the specific resolution and mass range requirements of the target application, whether it be environmental monitoring at parts-per-trillion levels or rapid clinical screening.
Application Verticals
Pharmaceutical and Biotechnology applications remain the primary revenue driver, reflecting the intense need for characterization in drug development. Academic and Research Institutes constitute a significant base, supported by public funding initiatives. Clinical Diagnostics is an emerging growth engine, propelled by regulatory clearances for automated platforms. Food and Environmental Testing represents a critical sector, increasingly driven by regulatory mandates rather than voluntary research.
Regional Distribution
While specific regional revenue figures are detailed in the full dataset, the global footprint is broad. North America, Europe, and Asia Pacific represent the major consumption hubs, with Latin America and the Middle East and Africa contributing to the global sum. Strategic expansion often depends on aligning local regulatory frameworks with laboratory infrastructure maturity.
Regulatory and Operational Dynamics Shaping 2026
Strategic decisions in 2026 cannot be made in a vacuum. Several regulatory and operational shifts have immediate implications for market participants.
- FDA Quality Management System Regulation: Effective February 2, 2026, the FDA's Quality Management System Regulation (QMSR) revises 21 CFR Part 820. This harmonizes device quality requirements with international standards. Manufacturers of HRMS systems used in clinical settings must ensure compliance to maintain market access, impacting supply chain and quality assurance protocols.
- Environmental Testing Mandates: The EPA's PFAS rule, effective January 2027, requires high-resolution systems for quarterly testing at detection limits below 4 ppt. This regulation creates a forced demand cycle for Orbitrap or Q-TOF systems in environmental monitoring laboratories, necessitating capacity planning for vendors and end-users alike.
- Funding and Capital Expenditure: Public sector support remains a key enabler. For instance, the NIH increased its structural-biology and proteomics budget to 2.1 billion USD in fiscal 2025, with specific earmarks for Orbitrap and Q-TOF high-resolution systems. This signals sustained government-backed demand for research-grade instrumentation.
What the Full Report Delivers
This executive summary provides the high-level trajectory, but the intricacies of market entry, competitive benchmarking, and risk mitigation require deeper data. The PW Consulting Worldwide High Resolution Mass Spectrometry System Market report offers granular insights designed for decision-makers who need precision comparable to the instruments they analyze.
Key deliverables included in the full study:
- Historical and Forecast Revenue Data: Detailed year-over-year revenue analysis from 2020 through 2032, broken down by macro segments to identify growth pockets.
- Segmentation Analysis: In-depth splits across technology types (TOF, Orbitrap, FT-ICR, Hybrid), application fields (Pharma, Academic, Clinical, Food/Environmental), and geographic regions.
- Competitive Profiling: Comprehensive profiles of key companies including product portfolios, recent launches, strategic moves, and market positioning.
- Regulatory Impact Assessment: Analysis of how FDA QMSR, EPA PFAS rules, and IVD clearances affect market dynamics and compliance costs.
- Strategic Assessments: Evaluation of market concentration, barriers to entry, and future industry trends affecting CapEx planning.
Conclusion: The Imperative for Precision Intelligence
The 2026 outlook for the High Resolution Mass Spectrometry System Market is one of calculated growth. With revenues projected to nearly double from 2025 levels by 2032, the opportunity is substantial. However, the complexity of regulatory compliance, the diversity of technological architectures, and the competitive intensity among top-tier manufacturers require more than surface-level analysis.
For organizations looking to invest, manufacture, or procure within this sector, understanding the specific revenue drivers behind the 8.12 percent CAGR and the implications of recent product launches from Thermo Fisher, Bruker, Waters, and others is essential. The detailed data segments, regional breakdowns, and competitive forecasts contained in the full PW Consulting report provide the roadmap necessary to navigate these complexities.
Stakeholders are invited to access the complete market intelligence package to leverage these insights for strategic planning. The full report contains the specific data points, regional valuations, and segmentation splits required to build robust business cases for the coming years.
For detailed analysis of this topic, please visit the official page: Worldwide High Resolution Mass Spectrometry System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Exterior Solar Shading Market to Hit $12,165.16M by 2032 at 4.65% CAGR
By PW Consulting, 2026-09-17
Navigating the Exterior Solar Shading Systems Market: Strategic Intelligence for 2026 and Beyond
The built environment stands at a critical intersection of architectural ambition and regulatory necessity. As global temperatures rise and energy codes tighten, the exterior solar shading systems market has evolved from a niche architectural feature into a core component of sustainable building infrastructure. For industry stakeholders, investors, and product strategists, understanding the trajectory of this sector is no longer optional—it is imperative for capital allocation and competitive positioning in 2026.
Solar Shading Systems Market
Our latest comprehensive analysis, the Worldwide Exterior Solar Shading Systems Market study, provides a granular look at the forces shaping this industry. This article serves as a strategic overview, highlighting the macroeconomic shifts, competitive maneuvering, and operational challenges that define the current landscape, while underscoring the decision-making value embedded in our full report.
The Macro Trajectory: Growth Amidst Volatility
The market has demonstrated resilience and consistent expansion over the past half-decade. Valued at approximately 7,125.4 million USD in 2020, the sector grew to an estimated 8,850.0 million USD by 2025. This historical performance sets a robust foundation for the forecast period spanning 2026 to 2032. During this window, the market is projected to advance at a CAGR of 4.65%, reaching a valuation of over 12,165.16 million USD by the end of the forecast horizon.
However, raw growth figures only tell part of the story. The pathway from 2026 to 2032 is not linear. Stakeholders must navigate a complex environment where demand drivers are strong, but supply-side constraints and cost pressures introduce volatility. For example, while the 2024 valuation saw a slight contraction to 8,063.1 million USD compared to 2023, the subsequent rebound in 2025 signals renewed momentum. Understanding the specific catalysts behind these fluctuations is essential for accurate forecasting, and our detailed analysis dissects these variances without relying on simplistic extrapolations.
Industry Dynamics: Regulation, Materials, and Technology
The expansion of the exterior solar shading market is being propelled by a convergence of regulatory mandates and technological innovation. Governments worldwide are increasingly recognizing the role of passive cooling and solar control in reducing carbon footprints. In the United Kingdom, Building Regulations Part L (Conservation of Fuel and Power) and Part O (Overheating) have placed significant emphasis on external solar shading to mitigate solar heat gain. These regulations are not mere suggestions; they are becoming critical compliance checkpoints for new builds, directly influencing specification rates.
Simultaneously, the European Union's Carbon Border Adjustment Mechanism (CBAM), effective as of January 2026, is reshaping supply chains. This regulation impacts the cost and availability of materials such as recycled aluminium, a staple in shading system manufacturing. For manufacturers and exporters, navigating CBAM compliance is now a strategic priority that affects pricing models and sourcing strategies.
On the technology front, the industry is witnessing a shift towards smart integration. Recent developments highlight this trend: in early 2025, Mado Dynamic launched AI-powered dynamic window shades equipped with solar-powered motors, signaling a move towards autonomous energy management. Similarly, TNO introduced a rollable shade screen with integrated solar foil, pushing the boundaries of material science to combine generation and protection. These innovations suggest that the future market winners will be those who can blend physical shading efficacy with digital control and energy autonomy.
Raw Material Pressures: The Aluminium Challenge
Cost management remains a pivotal concern for 2026 planning. Aluminium, a key material for extruded profiles in exterior solar shading systems, has experienced significant price volatility. Aluminium prices rose 25% year-on-year from USD 2,569 per tonne in January 2025 to USD 3,210 per tonne in January 2026. By mid-April 2026, the LME aluminium cash settlement price reached approximately USD 3,581 per tonne amid ongoing supply constraints.
This upward pressure on input costs threatens to squeeze margins unless offset by value engineering, premium pricing strategies, or supply chain diversification. Our report provides a deep dive into how these material costs interact with regional pricing sensitivities and product type margins, offering a clearer picture of where profitability can be preserved in a high-cost environment.
Competitive Landscape: Consolidation and Specialization
The market structure is characterized by a mix of global giants and specialized niche players. The top three companies hold a combined market share of 18.4%, while the top five control 24.55%. This fragmentation suggests that while leaders exist, there is ample room for competition and differentiation.
Key incumbents are defining the standard for quality and innovation. Hunter Douglas Inc., headquartered in the Netherlands, continues to leverage its global leadership status with a wide range of exterior solar shading systems, focusing heavily on energy efficiency and design integration for both commercial and residential sectors. In Germany, WAREMA Renkhoff SE specializes in high-quality solutions such as external venetian blinds and facade systems, increasingly incorporating advanced automation for climate control.
Automation is also a central theme for Lutron Electronics Co. Inc. in the USA, which provides integrated exterior shading systems and controls that emphasize smart automation and energy management for commercial buildings. Meanwhile, Kawneer (Arconic Corporation) offers architectural aluminum systems including exterior solar shading louvers, targeting high-performance building envelopes. Somfy Systems Inc. of France remains a leading provider of motorized automation and control systems, crucial for the operation of blinds and screens.
Regional specialization adds another layer of complexity. Duco Ventilation & Sun Control in Belgium focuses on ventilation-integrated systems for natural climate management, while Griesser AG in Switzerland emphasizes premium durability and Swiss engineering. Levolux Limited in the UK provides architectural brise soleil and adjustable louvers, and Markilux GmbH in Germany is known for high-end awnings and terrace covers. This diversity means that competitive strategy cannot be one-size-fits-all; it must be tailored to specific product types, applications, and geographic regulations.
Strategic Imperatives for 2026 Decision Makers
As we move through 2026, several strategic imperatives emerge for stakeholders in this sector:
- Supply Chain Resilience: With aluminium prices fluctuating and CBAM regulations active, companies must audit their supply chains for compliance and cost stability. Diversification of sourcing and investment in recycled content where permissible will be critical.
- Smart Integration: The market is shifting towards connected solutions. Partnerships with control system providers or internal development of IoT capabilities will distinguish products in a crowded field. The recent launch of synchronised solar shading ranges by players like Waverley indicates the direction of travel.
- Regulatory Alignment: Success in key markets like Europe and North America increasingly depends on demonstrating compliance with energy codes. Products that can verify energy savings and overheating reduction will gain preferential status in specification processes.
- M&A Activity: Consolidation is ongoing, exemplified by Nordic Alpha Partners acquiring all MicroShade assets and patents for 3D micro-structure engineering in glazing and shading systems in late 2025. This highlights the value of intellectual property in advanced shading technologies.
What the Full Report Reveals
While this overview captures the strategic tensions and growth vectors of the Worldwide Exterior Solar Shading Systems Market, it only scratches the surface of the intelligence available in our full study. The complete report offers a multi-dimensional analysis designed to support specific business decisions, from product development roadmaps to market entry strategies.
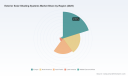
Inside the full document, readers will find detailed segmentation analysis that breaks down the market by region, product type, and application. We examine the distinct growth profiles of segments such as Roller Shutters, Awnings, External Louvers and Brise-soleil, and Solar Screens and External Blinds. Each segment faces unique demand drivers and competitive pressures that require tailored strategic responses.
Worldwide Exterior Solar Shading Systems Market
Furthermore, the report provides an application-focused view, analyzing how demand differs across Residential Buildings, Commercial Offices and Hospitality, and Public and Institutional Infrastructure. The commercial sector, for instance, may prioritize automation and energy management, while residential buyers might be more sensitive to cost and aesthetic integration. Understanding these nuances is vital for marketing and sales alignment.
Regional insights are also critical. The market dynamics in Europe differ significantly from those in North America or Asia Pacific, driven by varying regulatory environments, climate conditions, and architectural traditions. Our analysis maps these regional disparities, helping companies prioritize their geographic footprint and resource allocation.
Finally, the competitive profiling goes beyond basic company descriptions. We analyze recent developments, such as the Sun Shading Expo North America featuring new exterior sun shading systems and technical textiles, to identify emerging trends and potential disruptors. By tracking product launches, acquisitions, and innovation pipelines, we provide a forward-looking view of the competitive battlefield.
Conclusion: Turning Insight into Action
The Worldwide Exterior Solar Shading Systems Market is poised for continued growth, but the path forward is fraught with material cost risks, regulatory complexity, and rapid technological change. Companies that treat 2026 as a year for strategic recalibration—rather than mere operational continuity—will be best positioned to capture value.
We invite you to access the full market research report to unlock the detailed data, segmentation breakdowns, and competitive intelligence necessary to navigate this evolving landscape. Whether you are planning a product launch, evaluating a merger target, or optimizing your supply chain, the deep insights contained within this study will serve as a foundational tool for your 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Exterior Solar Shading Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Digital Scent Market Hits $1.44B in 2025, Projected $3.1B by 2032 at 11.64% CAGR
By PW Consulting, 2026-09-17
Beyond the Graph: Strategic Imperatives in the $3.1 Billion Digital Scent Revolution
The transition from visual and auditory digital interfaces to the olfactory realm has graduated from science fiction to a measurable economic force. As we step into 2026, the Worldwide Digital Scent Market presents a landscape defined by rapid technological convergence, regulatory maturation, and profound shifts in enterprise strategy. Our latest market research report, Worldwide Digital Scent Market, offers a granular, foresight-driven analysis designed to empower stakeholders navigating this volatile yet high-reward environment. The following essay distills the core strategic findings of the report, outlining the macro-market trajectory, competitive fault lines, and the operational imperatives that will define winners over the forecast period of 2026 to 2032.
The Macro Growth Trajectory: From Nascent Adoption to Mainstream Infrastructure
The digital scent market has undergone a structural acceleration since 2020, moving beyond early laboratory proofs to commercial deployment. According to our comprehensive modeling, the global market revenue stood at approximately $1.436 billion in 2025, demonstrating robust resilience and expansion year over year. Looking ahead, our forecast extends through 2032, projecting a steady compounding growth that drives market scale to an estimated $3.104 billion. This trajectory is underpinned by a compound annual growth rate (CAGR) of 11.64 percent across the forecast horizon.
This growth is not uniform but rather characterized by phased inflection points. The near-term period of 2026 through 2027 witnesses a foundational ramp-up as key industrial and consumer pilots mature into scaled rollouts. Mid-term forecasts indicate a marked acceleration, culminating in the market surpassing the $3.1 billion threshold by 2032. For strategic planners, this curve signals a critical window. The next 18 to 24 months represent the bridge between early-adopter experimentation and widespread infrastructure integration. Companies that fail to map their product roadmaps to this velocity risk ceding the high-margin segments of scent synthesis, digital olfaction analytics, and embedded olfactory electronics to more agile competitors.
Key Market Dynamics and the Competitive Architecture
The prevailing Competitive Landscape is shaped by a mix of established instrumentation leaders, specialized biotechnology firms, and disruptive AI-native entrants. Our analysis of the market concentration reveals a moderately fragmented structure, with the top three players accounting for 34.2 percent of revenue and the top five firms holding a combined 51.85 percent share. This equilibrium indicates a market where dominant incumbents set the technical standards but where specialized challengers retain significant room to capture niche leadership through proprietary sensor architectures and AI-driven scent mapping platforms.
Geographically, the market reflects mature industrial demand centers in North America, Europe, and the Asia Pacific region. These areas collectively drive the bulk of investment, reflecting deep penetration in healthcare diagnostics, food and beverage quality control, and advanced manufacturing environments. However, our regional analysis also highlights a nuanced divergence: whereas Europe and North America lean heavily into industrial diagnostics and environmental compliance, the Asia Pacific market exhibits distinct software and AI integration dynamics, emphasizing real-time scent digitization and sensory augmentation for consumer electronics. Latin America and the Middle East and Africa collectively represent emerging vectors, where early deployments in environmental monitoring and selective retail applications offer asymmetric growth opportunities for firms that prioritize localized sensor calibration and regional partnership models.
On the technology verticals, the market bifurcates primarily between electronic nose (e-nose) instruments and scent synthesizing peripherals. E-nose devices continue to dominate the analytical and diagnostic spend, serving as the core sensing layer for objective odor measurement across sectors. Meanwhile, scent synthesizers and other peripheral devices form the complementary delivery matrix, essential for programmable scent experiences, environmental control, and immersive interactive applications. The strategic implication is clear: the ecosystem is moving toward end-to-end stacks where sensing, data analytics, and output generation are increasingly integrated under unified software orchestration layers.
Real-World Deployments and the Acceleration of AI-Olfaction
The momentum driving the projected CAGR is vividly illustrated by recent high-impact developments. In early 2026, Osmo completed a $70 million Series B funding round, bringing its total capital raised to $130 million. This capital allocation signals a definitive shift to scaling AI-powered olfactory intelligence, moving beyond scent discovery into industrial-grade molecule mapping and custom fragrance generation. Simultaneously, Osmo published more new fragrance ingredient patents in 2025 than the entire rest of the major fragrance industry combined, a data point that underscores the disruptive pace at which AI-driven olfactory platforms are rewriting the innovation bottleneck.
On the application side, commercialization is accelerating across immersive and wearable interfaces. In December 2025, Scentient unveiled Escents, a new digital scent-emitting wearable device designed to pair with VR/AR environments. This launch represents a tangible bridge between sensor data and consumer-facing haptics, validating the viability of paired olfactory-visual augmentations. Concurrently, industrial automation is leveraging scent digitization for precision operations; in July 2025, Ainos partnered with Ugo, Inc. to pilot service robots equipped with AI Nose for industrial automation across seven sites in Japan. Such pilots demonstrate that scent is being quantified not merely as a subjective experience but as a measurable signal within automated workflows.
Worldwide Digital Scent Market
Further reinforcing the sector's maturity, Aryballe introduced its next-generation NeOse Advance platform in January 2025, integrating deep learning to improve real-time odor detection accuracy in industrial and healthcare markets. These ecosystem events collectively point to a market where investment, IP generation, and productization are reinforcing one another, compressing the typical diffusion curve for industrial sensing technologies.
The Regulatory and Standardization Imperative
Continued market expansion is inextricably linked to the formalization of standards and the establishment of ethical guardrails. As the Digital Olfaction Society articulated in its 2026 strategy, the industry is pivoting toward responsible development frameworks that address regulation, norms, and societal impact. This shift is timely. Ongoing efforts highlight unresolved consensus gaps around digital odor representation formats, heterogeneous sensor architectures, and the need for standardized, AI-oriented olfactory datasets. Proposals for normative implementation, including metadata exchange protocols for bio-digital convergence, are moving from academic discourse toward operational requirements.
Simultaneously, governance discussions are sharpening around the risks of robotic olfaction. Industry dialogues emphasize the necessity of governmental and institutional regulations to prevent misuse in odorveillance and to protect data privacy against surreptitious scent data collection. These concerns are not peripheral; they directly affect procurement cycles, liability exposure, and the long-term viability of deployed olfactory systems in regulated environments such as healthcare, public spaces, and consumer goods. For enterprises, proactive engagement with standardization bodies and the adoption of auditable, privacy-compliant scent data pipelines will transition from compliance hygiene to competitive differentiator.
Mapping Device and Application Segments: Where Value Is Created
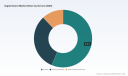
An effective investment thesis requires understanding the interlock between hardware categories and application verticals. The market is anchored by e-nose instruments that continue to capture the majority of analytical and diagnostic spend, reflecting the high demand for objective, repeatable odor measurement. These instruments serve as the sensing backbone for multiple downstream applications. Complementing this backbone is a growing cohort of scent synthesizers and other peripheral devices that enable controlled scent delivery, multi-scent sequencing, and environmental envelope modulation.
Application segmentation reveals a diversified demand surface. Healthcare and diagnostics represent a high-value vertical, driven by objective biomarker detection, quality control in sterile environments, and emerging therapeutic pathways linking olfactory stimuli to wellness and rehabilitative outcomes. Food and beverage quality control remains a cornerstone use case, where rapid, non-destructive scent analysis reduces waste and accelerates throughput. Entertainment and gaming, together with marketing and retail, are expanding the addressable market by integrating programmable scent into brand experiences, immersive environments, and differentiated consumer journeys. Environmental monitoring rounds out the portfolio, applying digital olfaction to air quality assessment, emissions tracking, and industrial safety compliance.
Strategic prioritization in these segments is not a simple matter of market size. The highest value capture occurs where digital scent technology is embedded into mission-critical workflows rather than serving as a peripheral novelty. Our analysis indicates that firms aligning sensor accuracy, real-time data processing, and seamless integration with existing enterprise software stacks achieve superior unit economics and longer contract durations. Conversely, applications that rely solely on standalone scent delivery without robust sensing or analytics tend to face higher churn and lower margin profiles.
Integrating the Intelligence: How to Use This Report
This Worldwide Digital Scent Market research is constructed for decision-makers who must convert market signals into actionable strategy. The report goes beyond headline figures to provide a multi-dimensional decomposition of the opportunity landscape. Stakeholders will find a detailed review of device categories and application verticals, contextualized by regional adoption patterns and competitive intensity. The report maps the core ecosystem participants and their strategic profiles, enabling readers to identify both alliance candidates and areas of potential disruption.
Beyond segmentation, the report examines market concentration dynamics, the pace of standardization efforts, and the evolving regulatory perimeter. It synthesizes recent funding events, product launches, patent activity, and pilot deployments to chart the tempo of innovation and capital allocation. Readers will also find frameworks for assessing where the market is likely to consolidate versus where fragmentation will persist, which in turn informs M&A prioritization, partnership strategy, and go-to-market sequencing. The depth of this intelligence allows procurement, product management, and corporate development teams to stress-test assumptions against the most current market signals rather than relying on stale secondary sources.
Crucially, the report is designed to be operational. It translates macro trends into decision checklists regarding sensor technology roadmaps, digital scent integration architectures, and the timing of market entry across key verticals. It also identifies the structural factors that will determine which companies can sustain growth as the market scales, including IP positioning, standards participation, and the ability to deliver end-to-end solutions that span sensing, analysis, and delivery.
Conclusion: Positioning for the Olfactory Digital Economy
The Worldwide Digital Scent Market is entering a phase where technological promise is continuously converting into commercial reality. With a projected 11.64 percent CAGR driving the sector toward $3.104 billion by 2032, organizations that act now can secure advantageous positions in sensing, synthesis, and digital olfaction analytics. Yet the window for opportunistic advantage is narrowing. Standardization, privacy and ethical norms, and the consolidation of AI-enabled scent platforms are reshaping the rules of engagement. Success will belong to those who combine rigorous technical evaluation with forward-looking engagement in standards, regulatory dialogue, and strategic partnerships.
This report provides the granular intelligence needed to navigate that transition with confidence. The macro figures set the stage, the competitive and dynamic analyses map the field, and the operational frameworks give leadership the tools to convert insight into execution. To unlock the full segmentation detail, competitor profiles, regional adoption maps, and actionable decision frameworks embedded in our analysis, we invite you to access the complete Worldwide Digital Scent Market research on our platform.
Digital Scent Technology Market
For detailed analysis of this topic, please visit the official page: Worldwide Digital Scent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Anti-Blue Ray Myopia Lens Market to Hit $7,416.29M by 2032, 8.15% CAGR
By PW Consulting, 2026-09-17
Beyond Correction: Strategic Intelligence for the Worldwide Anti-Blue Ray Myopia Lenses Market (2026–2032)
The Convergence of Myopia Management and Digital Eye Protection
The global optical industry is undergoing a fundamental transformation. For decades, spectacle lenses were viewed primarily as corrective devices. Today, they have evolved into therapeutic interventions and protective wearables simultaneously. This shift is most evident in the Worldwide Anti-Blue Ray Myopia Lenses Market, where the dual imperatives of slowing pediatric myopia progression and mitigating digital eye strain are converging into a single, high-growth product category.
As organizations prepare their strategic roadmaps for 2026 and beyond, understanding the magnitude and mechanics of this convergence is no longer optional. It is a prerequisite for capacity planning, R&D allocation, partnership strategy, and competitive positioning. Our latest research release, the Worldwide Anti-blue Ray Myopia Lenses Market study, provides the analytical scaffolding required to navigate this complex landscape with precision.
Market Trajectory: From Recovery to Sustained Expansion
The historical trajectory of the market tells a compelling story of acceleration. Driven by rising global prevalence of myopia, particularly among school-aged children, and compounded by prolonged screen exposure across age groups, the market has moved steadily upward over the past half-decade. From a baseline in 2020, the segment has consistently expanded year-over-year, reflecting both increased diagnosis rates and broader consumer acceptance of functional lens designs.
Looking forward, the forecast period from 2026 through 2032 projects a compound annual growth rate of 8.15 percent. This sustained expansion signals that the category is transitioning from a niche innovation to a mainstream optical staple. The revenue trajectory suggests that by the early 2030s, the market will have more than doubled its size relative to the mid-2020s baseline. For executives, this growth curve is not merely a statistical indicator—it represents a widening window of opportunity for first-mover advantages in distribution, manufacturing scale, and clinical credibility. The strategic question for 2026 is no longer whether to invest in this space, but how to allocate resources to capture disproportionate value as the market matures.
The Technological Calibration: Substrate Absorption, Coatings, and Myopia-Control Optics
The product architecture underpinning this market is becoming increasingly sophisticated. Modern anti-blue ray myopia lenses are no longer simple filtered substrates. They represent a careful engineering balance between optical clarity, material index selection, and therapeutic optics. Manufacturers are leveraging substrate absorption technologies—such as UV420 blue light absorption factors—alongside advanced anti-reflective coatings to achieve blue light filtering without compromising visual fidelity.
Simultaneously, the myopia management component relies on peripheral defocus or diffusion optics designs, integrated into high-index resin materials across indices ranging from 1.499 to 1.74. The result is a functional lens that addresses two distinct clinical needs: reducing the rate of axial elongation in progressing myopes, and minimizing digital eye strain associated with extended near-work and screen exposure. This dual-function design philosophy is reshaping product development cycles, coating specifications, and inventory strategies across the value chain. Companies that can effectively communicate the clinical and experiential benefits of these integrated designs will hold a distinct advantage in prescription conversion and consumer loyalty.
Regulatory Inflection Points and Clinical Validation
One of the most significant catalysts reshaping market dynamics is the evolving regulatory environment. In September 2025, the U.S. Food and Drug Administration granted marketing authorization for Essilor Stellest eyeglass lenses, marking the first spectacle lens indicated to slow the progression of pediatric myopia in children ages six to twelve. This authorization was based on clinical data demonstrating a substantial reduction in myopia progression compared to single vision lenses. The FDA decision does more than validate a single product line; it establishes a precedent that opens the door for increased scrutiny, increased consumer trust, and increased prescription momentum across the broader myopia management category.
Parallel to this milestone, other major manufacturers have secured CE marking and FDA registration or authorization for their peripheral defocus and diffusion optics lenses, enabling distribution in key markets with recognized quality and safety benchmarks. These regulatory milestones are not abstract compliance achievements; they are direct enablers of prescriber confidence. When eye care professionals can reference authorized or registered products with documented clinical outcomes, the barrier to adoption drops significantly. For 2026 planning, organizations must factor regulatory status into their market entry strategies, partnership evaluations, and messaging architectures. The companies that can align their product narratives with clinical evidence and regulatory clarity will capture the prescribing share in an increasingly evidence-driven market.
Worldwide Anti-blue Ray Myopia Lenses Market
Distribution Realignment: Retail, Clinical, and Digital Channels
The path to the end user is undergoing structural change. Historically, optical retail stores have served as the dominant distribution backbone, supported by ophthalmic clinics and hospitals where prescriptions originate. Today, that hierarchy is being supplemented—and in some segments, disrupted—by the growth of online e-commerce platforms.
The coexistence of these channels creates a complex commercial landscape. Optical retail stores benefit from immediate fitting, in-person consultation, and after-sales service, which remain critical for pediatric prescriptions where frame selection, lens centration, and parent education all influence purchase decisions. Clinics and hospitals carry the authority of professional recommendation, making them essential gateways for myopia management products that require clinical endorsement. Meanwhile, online platforms are expanding reach, reducing friction for repeat purchases, and enabling direct-to-consumer education campaigns that build category awareness before a prescription is even written.
For 2026 strategy, the critical insight is that channel excellence is no longer about choosing one pathway; it is about orchestrating a multi-channel presence that matches the customer journey. Companies must evaluate where their product fits within each channel's operational model, how prescription capture occurs, and how service expectations differ. The market leaders will be those who can synchronize inventory, pricing, and brand messaging across physical and digital touchpoints without diluting the clinical credibility of the product.
Competitive Landscape: Incumbents, Specialists, and the Race for Differentiation
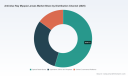
The competitive field in this market is characterized by a blend of global vision care giants and specialized manufacturers, each pursuing distinct strategies to secure share. At the top tier, conglomerates such as EssilorLuxottica, HOYA Vision Care, and ZEISS are leveraging substantial R&D budgets, established prescription networks, and brand recognition to push the frontier of myopia management optics. These players are not only competing on lens efficacy but also on coating durability, aesthetic design, and the breadth of their myopia control portfolios.
In parallel, a robust cohort of manufacturers—particularly from China, Japan, and Israel—is competing on material range, coating innovation, and value-positioning. Companies such as Jiangsu Green Stone Optical, Zhenjiang Select Optical, YOULI, Shanghai Conant Optics, Mingyue Glasses, Nikon, and Shamir Optical Industry are producing resin spectacle lenses with integrated anti-blue ray functionality, photochromic options, and infrared cut capabilities across a wide range of indices. Several of these firms carry CE and FDA registrations along with ISO9001 and ISO14001 certifications, enabling them to compete in regulated markets while offering flexible index options and cost-efficient manufacturing.
This dynamic creates a market structure where concentration is significant but not absolute. The leading players collectively command a substantial share of revenue, reflecting the advantages of brand equity, clinical partnerships, and global distribution. Yet the presence of capable mid-tier and regional manufacturers sustains pressure on pricing, accelerates feature innovation, and expands the overall supply base. For 2026 decision-makers, the strategic challenge is twofold: protect and extend position if you are an incumbent, or identify the segment, channel, or technology niche where differentiation can be achieved without triggering a direct confrontation with the largest brands.
Myopia Control Lens (Plastic Lens) Market
Recent Developments as Strategic Signals
Recent product and regulatory events offer a window into the direction the market is heading. In September 2025, the FDA authorization of Essilor Stellest lenses established a new benchmark for spectacle-based myopia control. In October 2025, HOYA introduced its Smooth Touch Xtreme coating on MiYOSMART lenses, pairing long-lasting hydrophobic performance with sustained blue light filtering—an enhancement that directly addresses practical consumer concerns around cleanliness, durability, and everyday usability. Later, in December 2025, EssilorLuxottica expanded its myopia management platform with Stellest 2.0 lenses powered by enhanced H.A.L.T. MAX technology, signaling that the innovation cycle is accelerating rather than plateauing.
These developments are more than product announcements. They are strategic signals. They indicate that coating technology, material durability, and next-generation optical designs are becoming decisive battlegrounds. They also suggest that manufacturers are racing to bundle clinical efficacy with tangible daily benefits, because the prescribing decision and the purchase decision are increasingly influenced by both evidence and experience. Organizations planning for 2026 must assess where their own technology roadmap aligns with these vectors and where gaps in coating, index range, or design architecture could become liabilities.
What the Research Delivers: Actionable Intelligence for 2026 Planning
Our Worldwide Anti-blue Ray Myopia Lenses Market report is designed to convert market complexity into executable strategy. Rather than offering a static snapshot, the study structures the market around the dimensions that matter most to commercial and operational decision-making.
The report provides a detailed segmentation analysis across lens materials, distribution channels, and regional markets. This breakdown enables teams to identify which material categories are gaining traction, which channels are driving prescription and purchase volume, and where regional dynamics are creating distinct growth environments. The analysis also includes a comprehensive competitive profiling of the key companies shaping the market, with headquarters, product strategies, and positioning insights that support benchmarking and partnership evaluation.
Beyond segmentation, the study examines market concentration dynamics, offering visibility into how revenue is distributed among leading players and what that implies for competitive intensity and entry barriers. The report further integrates the market context that shapes demand: the role of increased screen time in driving functional lens adoption, the material and coating technologies that define product performance, and the regulatory developments that are lowering or raising barriers in specific geographies.
Crucially, the research is built to support practical outputs. It can inform manufacturing capacity decisions, SKU architecture, coating investment priorities, channel partner selection, and geographic expansion sequencing. It provides the evidence base needed to justify R&D allocation toward myopia control optics and anti-blue light functionality, and it equips commercial teams with the segmentation intelligence required to target prescribers, retailers, and end consumers with precision.
The 2026 Decision Window: Why This Research Matters Now
2026 is a pivotal year for this market. The growth trajectory is established, the technology options are multiplying, and the regulatory environment is reinforcing clinical credibility. At the same time, the competitive field is tightening, and channel expectations are becoming more sophisticated. Organizations that enter this year with fragmented intelligence risk misallocating resources, over-indexing on saturated segments, or underestimating the importance of clinical and regulatory positioning.
The Worldwide Anti-blue Ray Myopia Lenses Market report is structured to close that intelligence gap. It provides the macro context, segmentation depth, competitive mapping, and dynamic insights needed to make informed choices about where to play and how to win. By translating growth signals into a structured strategic framework, the research enables leadership teams to align product development, commercial execution, and market entry timing with the realities of a rapidly evolving category.
Next Steps for Strategic Alignment
To leverage this intelligence effectively, organizations should begin by stress-testing current assumptions against the market's segmentation realities. Which lens material categories align with your manufacturing capabilities and margin targets? Which distribution channels match your service model and prescription capture strategy? Where does your regulatory status place you relative to competitors in key markets? Answering these questions with the support of detailed market data will sharpen strategic focus and reduce execution risk.
The full study provides the complete segmentation values, regional revenue figures, material-level breakdowns, and channel-level analysis that support these decisions. We invite you to access the source page for the complete dataset, the detailed company profiles, and the extended market dynamics discussion. In a market expanding at this pace, the difference between reactive positioning and proactive strategy is often a matter of how early and how precisely you can read the signals. This research is built to help you do exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-blue Ray Myopia Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dairy-Free Infant Formula Market Hits $2.65 Billion in 2025, Projected to Hit $4.21 Billion by 2032
By PW Consulting, 2026-09-17
Global Dairy-Free Infant Formulas Market: Strategic Intelligence for 2026 and Beyond
The worldwide dairy-free infant formulas market stands at a critical inflection point in 2026. Driven by rising consumer awareness of infant sensitivities, evolving regulatory frameworks, and sustained demand for clean-label nutrition, this segment has transformed from a niche alternative into a structural pillar of the broader infant nutrition industry. Our latest comprehensive market research provides decision-makers with the analytical rigor required to navigate rapid category evolution, allocate capital efficiently, and position portfolios against compounding structural shifts.
Worldwide Dairy-Free Infant Formulas Market
Between 2020 and 2025, the market expanded from approximately $1.90 billion to $2.65 billion, reflecting a compound annual growth trajectory that has consistently outpaced conventional infant formula categories. Forward-looking projections through 2032 indicate sustained momentum, with the market anticipated to exceed $4.2 billion by the end of the forecast horizon. The intervening years will be shaped by evolving product architecture, channel migration, and regulatory recalibration. Understanding the mechanics behind these movements is no longer optional; it is a prerequisite for market leadership.
Why This Research Matters for 2026 Strategic Planning
Corporate strategy in infant nutrition requires more than high-level trend narratives. Executives evaluating product portfolio expansions, supply chain adjustments, or regional market entries need granular, actionable intelligence that connects macro market behavior to operational decision-making. This report is engineered to serve as a centralized strategic reference, translating complex market signals into structured insights that can be operationalized across R&D, commercial, regulatory, and M&A functions.
The analysis isolates the forces that will define competitive positioning throughout the forecast period. These include the maturation of soy-based formulations, the scientific and regulatory pathway evolution for hydrolyzed and amino acid-based alternatives, and the emergence of novel plant-based architectures that appeal to clean-label and flexitarian caregiver preferences. Each of these vectors carries distinct implications for formulation strategy, manufacturing complexity, and consumer trust.
Equally important is the shift in distribution dynamics. Retail infrastructure continues to recalibrate around omnichannel access, with traditional physical retail channels adapting to digital-native purchasing behaviors. The report dissects how these channels interact with product positioning, pricing architecture, and consumer discovery patterns, enabling brands to align go-to-market strategies with actual purchasing behavior rather than legacy assumptions.
Market Structure and Growth Architecture
The market's expansion has been supported by durable demand drivers rather than short-lived trend cycles. Caregivers increasingly seek formulas that address milk protein sensitivity, lactose intolerance, and broader digestive sensitivities, while simultaneously demanding ingredient transparency and nutritional completeness. This convergence has sustained category relevance across varying economic conditions and demographic segments.
Revenue composition reflects a diversified product landscape. Soy-based architectures represent a substantial portion of the dairy-free formula universe, leveraging established manufacturing pathways and recognized nutritional profiles. Hydrolyzed and amino acid-based formulations constitute a parallel pillar, addressing medically adjacent sensitivities and specialty nutritional requirements. A third, rapidly evolving segment encompasses other plant-based formulas that rely on non-soy botanical inputs and whole-food-inspired ingredient strategies. Each architecture carries distinct formulation requirements, cost structures, and consumer perception profiles.
Geography further shapes market behavior. Regional demand patterns are influenced by differing regulatory traditions, cultural attitudes toward plant-based infant nutrition, and the maturity of specialty retail ecosystems. North America, Europe, Asia Pacific, and Rest of World markets each exhibit distinct adoption curves and distribution characteristics. The report examines these differences not as isolated snapshots, but as interconnected elements of a global supply and demand system that multinational and regional players must navigate simultaneously.
Pricing dynamics and market concentration add further strategic complexity. A concentrated participant base holds meaningful share, which shapes competitive responses, innovation pacing, and barrier-to-entry calculations. At the same time, private-label manufacturing and store-brand expansion have introduced additional price architecture variability across channels. These structural factors influence margin expectations and portfolio positioning decisions in ways that must be modeled explicitly rather than assumed.
Competitive Landscape: Navigating Portfolio, Regulation, and Positioning
The competitive environment is defined by a mix of global incumbents, scientifically oriented specialists, and emerging clean-label innovators. Each participant approaches the dairy-free infant formula category through a distinct strategic lens, and understanding these differences is essential for evaluating partnership opportunities, benchmarking positioning, and anticipating competitive responses.
Abbott Laboratories continues to anchor its presence with established soy-based offerings that address milk protein sensitivity and lactose intolerance, leveraging scale, clinical heritage, and broad distribution access. Reckitt Benckiser, through its Mead Johnson heritage, maintains a strong position with plant-based soy formulations designed for sensitive digestive systems, reinforced by global marketing infrastructure and long-standing caregiver recognition. Nestlé S.A. approaches the category through a diversified infant nutrition portfolio, integrating dairy-free and plant-blend options that address sensitivities while preserving access to wider nutritional platforms. Danone S.A. similarly deploys plant-blend and specialty formulations across premium and therapeutic-adjacent positioning, using its Nutricia and related brand architecture to reach caregivers seeking hybrid dairy and plant combinations aligned with vegetarian or flexitarian preferences.
Beyond the large multinationals, a distinct set of specialists is shaping category innovation. Else Nutrition Holdings Inc. has moved toward whole-food plant-based, non-soy, non-dairy formulations built on almonds, buckwheat, and tapioca, targeting caregivers who prioritize clean-label composition and avoid both dairy and soy. Sprout Organic and Earth's Best extend the organic and plant-based frontier, with Earth's Best reinforcing non-GMO and vegan-sourced DHA positioning within an organic soy-based dairy-free framework. Perrigo Company plc plays an important structural role through store-brand and private-label manufacturing, ensuring that regulatory-compliant dairy-free and soy-based formulas remain accessible across retail ecosystems. Hain Celestial Group contributes organic and plant-based options that align with broader natural-ingredient consumer expectations, while Bobbie emphasizes organic formulation principles with plant-based elements designed for dairy-sensitive needs.
Recent Developments Shaping Strategic Decision-Making
The market environment in 2025 and early 2026 has been influenced by regulatory developments, product launches, and supply-chain events that directly affect category planning. These developments are not isolated news items; they are indicators of the operating conditions businesses will face throughout the forecast period.
Regulatory progress has been particularly consequential. In early 2026, the FDA listed Protein Efficiency Ratio rat bioassay study guidance as active, reinforcing a scientific validation pathway relevant to novel plant-based, non-soy infant formula architectures. For companies pursuing alternative protein systems, this signals a more defined route toward US commercialization and reduces ambiguity around evidence expectations. At the same time, broader regulatory momentum continues to reshape category boundaries. The FDA's uniform compliance dates for food labeling regulations spanning 2025 through 2026, together with guidances on allergen labeling and plant-based alternative labeling, directly affect how dairy-free claims and nutrient statements can be communicated. These rules influence packaging strategy, claim architecture, and consumer messaging across all participants.
Operation Stork Speed, launched in 2025, has added another regulatory layer by initiating updates to infant formula nutrient regulations that had remained largely unchanged since the 1980s and 1990s. Protein quality pathways are especially relevant for novel plant-based, non-soy formulations, making this initiative a key variable for R&D planning and clinical substantiation strategies. In parallel, US Congressional appropriations for fiscal year 2026 include report language directing the FDA to streamline regulatory pathways specifically for plant-based, non-soy, non-dairy infant formulas. This legislative signal expands the strategic conversation from compliance alone to potential category expansion and faster time-to-market for alternative architectures.
Supply-side events have also reinforced the importance of resilience planning. In late 2025, broad recalls involving infant formulas emerged due to cereulide toxin concerns linked to an ARA oil supplier, affecting multiple major manufacturers across several countries. While not limited to dairy-free products, the episode highlighted the interconnected nature of ingredient sourcing, quality assurance, and global recall exposure. For dairy-free formula strategists, the event underscores the need for robust supplier qualification, formulation redundancy, and transparent crisis communication frameworks.
On the commercial side, recent product activity continues to signal category vibrancy. New launches and retail rollouts in adjacent infant formula spaces indicate ongoing investment in the broader category, even when specific variants are not dairy-free. Such activity influences shelf visibility, caregiver trial behavior, and competitive intensity, all of which shape go-to-market calculations for dairy-free portfolios.
Report Scope: What Decision-Makers Will Gain
This market research is designed to provide an integrated view of the category rather than a fragmented collection of statistics. The report combines historical performance analysis, forward-looking forecasting, and structural decomposition to support strategy formulation across multiple functional domains.
The core content includes:
- A comprehensive market sizing framework covering the historical period and the full forecast horizon, enabling revenue trajectory modeling and baseline scenario planning.
- Segment-level analysis by product type, distribution channel, and region, structured to reveal where growth is concentrating and how category architecture is evolving.
- Competitive profiling of leading participants, with attention to product strategy, brand positioning, and the strategic implications of recent corporate and regulatory developments.
- Assessment of market concentration dynamics and their implications for pricing power, entry barriers, and incumbent response patterns.
- Regulatory and labeling context relevant to dairy-free claims, plant-based nomenclature, nutrient compliance, and novel protein validation pathways.
- Channel behavior analysis that connects retail and online purchasing patterns to product positioning and commercial execution.
- Strategic FAQs and operational considerations that translate technical and regulatory detail into practical decision-making guidance.
By linking quantitative structure with qualitative industry context, the report enables leadership teams to evaluate opportunity sizing, risk exposure, and strategic fit without relying on superficial trend assumptions.
Strategic Imperatives for the Forecast Period
As the market advances through the remainder of the decade, several strategic imperatives will separate adaptive organizations from those that underperform relative to category momentum.
First, formulation strategy must balance nutritional credibility with consumer-facing clarity. Dairy-free infant formulas operate in a category where caregivers scrutinize ingredient origin, protein quality, and digestive compatibility. Products that align scientific substantiation with clean-label expectations will have an advantage in trust formation, particularly as alternative protein architectures gain regulatory and commercial traction.
Second, distribution strategy should be treated as a growth lever rather than a fulfillment endpoint. The interaction between physical retail, online channels, and specialty outlets increasingly determines product discovery, repeat purchase behavior, and price perception. Brands that align channel mix with target caregiver behavior will be better positioned to convert demand into durable share.
Goat Milk Infant Formula Market
Third, regulatory readiness should be embedded into product development timelines. The evolving FDA guidance environment, nutrient regulation updates, and legislative signals around plant-based, non-soy pathways all affect time-to-market, claim eligibility, and market access. Organizations that integrate regulatory scenario planning into R&D and commercial planning will reduce execution risk and improve responsiveness to policy shifts.
Fourth, supply-chain resilience will remain a differentiator. Ingredient sourcing, supplier qualification, and recall readiness are no longer back-office concerns. They are strategic capabilities that influence brand trust, inventory continuity, and market reputation. As global supply networks remain exposed to quality and contamination risks, proactive resilience planning will be a competitive advantage.
Finally, portfolio architecture should reflect both specialization and scalability. Dairy-free infant formulas can serve broad sensitivity-driven demand, specialty nutritional needs, and premium clean-label positioning. The most effective portfolios will combine these layers without diluting focus, ensuring that each product architecture supports a clear consumer proposition and a defensible commercial position.
Conclusion
The worldwide dairy-free infant formulas market will continue to expand, but growth alone will not guarantee competitive success. The strategic winners in 2026 and beyond will be those who understand the interaction between product architecture, regulatory evolution, channel behavior, and supply-chain resilience. Our latest market research provides the structured intelligence required to make those decisions with confidence.
The full report Contains the detailed segmentation analysis, forecast modeling, competitive assessments, and operational context needed to translate category momentum into concrete business strategy. We invite executives, strategy teams, and commercial leaders to access the complete market intelligence and use it to shape portfolio decisions, investment priorities, and market-entry planning for the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Dairy-Free Infant Formulas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Circuit Breaker Market Hits $540M in 2025, 6.0% CAGR to $812M by 2032
By PW Consulting, 2026-09-17
Navigating the Classified Circuit Breaker Landscape: Strategic Intelligence for 2026 and Beyond
The global electrical safety and power distribution ecosystem is undergoing a structural transformation. As infrastructure ages, regulatory standards tighten, and digitalization reshapes equipment expectations, the UL-Classified circuit breaker segment has emerged as a critical nexus for manufacturers, distributors, contractors, and facility operators. Understanding where this market stands today—and where it is heading through 2032—requires more than surface-level headline figures. It demands a rigorous, data-grounded assessment of growth trajectories, competitive positioning, material dependencies, and the regulatory frameworks that define interchangeability and safety compliance.
PW Consulting’s newly released Worldwide Classified Circuit Breaker Market study is designed precisely for that purpose. Built on a foundation of historical tracking from 2020 through 2025 and extended forecast modeling through 2032, the research translates market signals into actionable strategy. For executives formulating 2026 investment plans, capacity allocations, procurement frameworks, and competitive responses, this report serves as a decision-grade intelligence asset. What follows is a strategic preview of the market architecture, the forces reshaping it, and the analytical depth available in the full study.
Market Trajectory: A Decade of Measured Expansion
The classified circuit breaker sector has demonstrated consistent, compounding growth over the past half-decade, reflecting broader trends in electrical infrastructure renewal, residential renovation cycles, commercial retrofitting programs, and industrial maintenance spend. Historical revenue data shows a market that navigated short-term volatility while establishing a clear upward slope. In 2020, global revenue stood at approximately 410.5 million USD. The subsequent years marked a period of recovery and acceleration, with 2025 closing at 540.0 million USD. This progression underscores a market that has moved beyond post-pandemic normalization into a phase of sustained demand generation driven by replacement cycles, code updates, and modernization initiatives.
The forward outlook reinforces this momentum. Forecasted revenue progresses from 578.59 million USD in 2026 to 811.96 million USD by 2032, embedding a compound annual growth rate of 6.0 percent across the projection window. This trajectory is not merely a linear extrapolation; it reflects the cumulative impact of loadcenter compatibility expansions, third-party classified adoption, and the gradual migration of legacy panels into upgraded safety and performance configurations. For strategic planners, the implication is clear: the market is large enough to support meaningful share capture, yet dynamic enough that timing, product alignment, and regional execution will separate leaders from laggards.
Electronic Circuit Breaker Market
Structural Composition: Type, Application, and Regional Architecture
The classified circuit breaker market is shaped by a layered segmentation structure that influences pricing, channel strategy, manufacturing focus, and go-to-market execution. At the product level, the landscape is anchored by two principal categories: miniature circuit breakers and molded case circuit breakers. Miniature circuit breakers dominate the revenue mix, reflecting their extensive deployment in residential loadcenters, light commercial panels, and replacement-driven retrofit activity. Molded case circuit breakers, while smaller in aggregate revenue share, represent a strategically vital segment for industrial maintenance, higher-current applications, and environments where durability, interrupt capacity, and serviceability are non-negotiable.
Application-side demand further differentiates execution priorities. Residential renovation continues to be a powerful demand engine, fueled by aging housing stock, safety upgrading mandates, and consumer-driven electrical modernization. Commercial retrofitting adds a complementary layer of volume, particularly in office, retail, and multi-family properties where panel compatibility and code compliance shape procurement decisions. Industrial maintenance, though smaller in relative scale, contributes critical margin characteristics and recurring demand patterns tied to operational uptime, predictive maintenance programs, and facility lifecycle planning.
Regionally, the market exhibits a concentrated but geographically diverse demand profile. North America accounts for the largest share of revenue, reflecting the depth of loadcenter installed bases, the maturity of UL-classified interchangeability frameworks, and robust renovation and retrofit activity. Europe follows as a substantial market, supported by industrial infrastructure, commercial building upgrades, and evolving safety standards. Asia Pacific represents a significant and expanding base, where urbanization, grid investments, and manufacturing output continue to stimulate electrical equipment demand. Latin America and the Middle East and Africa, while smaller in absolute terms, offer incremental growth opportunities tied to infrastructure development, selective regional assembly strategies, and trade dynamics.
The full report decomposes these structural elements with greater precision, mapping how type, application, and regional drivers interact to shape volume, pricing, and competitive accessibility. Rather than presenting detached split data, the analysis emphasizes the strategic interplay between segments—where compatibility advantages, channel reach, and product portfolios determine which manufacturers can scale efficiently and which face structural constraints.
Competitive Dynamics: Incumbents, Compatibility, and Strategic Differentiation
The competitive field in the classified circuit breaker market is defined by a blend of broad-line electrical suppliers, specialized replacement-focused manufacturers, and global industrial players with extensive low- and medium-voltage portfolios. Market concentration remains meaningful, with the top three competitors collectively representing over half of revenue and the top five exceeding two-thirds. This concentration reflects the advantages of scale, established loadcenter compatibility, channel relationships, and brand trust in a category where safety certification and interchangeability are paramount.
Eaton Corporation maintains a particularly broad compatibility position, offering UL-Classified circuit breakers across multiple formats that align with loadcenters from General Electric, Siemens, Murray, Square D, and others. Its portfolio spans arc fault, ground fault, surge, and thermal magnetic protection, reinforcing its role as a cross-compatible replacement provider. Connecticut Electric competes with a focused replacement-oriented lineup, supplying UL-Classified breakers for residential and commercial loadcenters where compatibility and availability are the primary purchase drivers. Siemens participates with classified-compatible options, including replacements designed for Square D Type QO panels, while also leveraging its broader global breaker portfolio.
ABB Ltd brings scale across low, medium, and high voltage segments, with industrial, utility, and commercial applications forming the backbone of its circuit breaker business. Its classified-compatible solutions extend its reach into replacement and retrofit contexts where institutional procurement standards and performance requirements intersect. Schneider Electric, including its Square D branded heritage, demonstrates strong positioning in loadcenters and breaker ecosystems, with compatibility that allows third-party classified replacements to function across its platforms. General Electric, through GE Vernova, supplies breakers and loadcenters that accept UL-Classified replacements while also offering its own residential and commercial product lines.
The competitive field also includes a growing manufacturing presence from Asia and specialized industrial suppliers. CHINT Group has expanded its visibility through trade engagement and regional assembly initiatives, including recent demonstrations of power distribution solutions and local assembly activity aimed at strengthening supply chain resilience. Mitsubishi Electric contributes molded case and industrial-grade breakers with global reach. LS Electric supplies low and medium voltage breakers with an established international footprint. Fuji Electric focuses on power distribution and industrial applications, reinforcing the breadth of options available to buyers seeking industrial-grade performance alongside residential and commercial replacement demand.
Worldwide Classified Circuit Breaker Market
Recent industry activity underscores how competition is evolving beyond traditional product specs. In early 2026, CHINT highlighted an expanded exhibition presence and announced local assembly of air circuit breakers to reinforce regional supply commitments. Hager showcased prototypes of digitally enabled circuit breakers targeted at industrial applications, signaling imminent certification-driven launches. CNC Electric exhibited smart circuit breakers and intelligent devices at a major industrial trade event. These developments illustrate a broader shift in which manufacturers are not only competing on compatibility and price, but also on digital functionality, regional sourcing, and the ability to align product roadmaps with emerging certification timelines.
The complete study maps these competitive positions in greater detail, examining how product breadth, loadcenter compatibility networks, channel strength, and regional manufacturing strategies create differentiation. It also evaluates where entry barriers remain high, where substitutability pressures intensify, and how incumbent advantages can be defended or disrupted over the forecast horizon.
Industry Forces Shaping Demand and Execution Risk
Several structural dynamics are redefining how classified circuit breakers are specified, sourced, and deployed. Regulatory and safety frameworks remain central to market behavior. UL classification and listing establish the technical basis for safe mechanical and electrical interchangeability across loadcenters from multiple original manufacturers. This framework enables third-party replacement supply while preserving performance and safety expectations in residential and light commercial panels. Eaton’s compatibility reach, encompassing a wide range of loadcenters, illustrates how interchangeability can become a strategic moat when executed at scale. At the same time, manufacturers must continuously align with evolving standards, testing requirements, and listing obligations to maintain market access.
Material supply chains introduce another layer of strategic consideration. Circuit breaker manufacturing depends on copper, steel, and specialized polymers for contacts, housings, and insulation components. Material cost volatility, availability constraints, and sourcing geography can influence margin profiles and production planning, particularly for manufacturers balancing global scale with regional fulfillment expectations. Companies that manage material exposure through specification optimization, supplier diversification, and regional assembly strategies are better positioned to protect competitiveness during periods of input pressure.
Macro trends are also accelerating innovation and demand formulation. Grid modernization, renewable energy integration, and the adoption of digital or smart circuit breakers with remote monitoring capabilities are reshaping buyer expectations. These trends do not merely expand the addressable market; they alter the criteria by which products are evaluated. Electrical safety remains foundational, but connectivity, diagnostics, and integration with broader building or industrial management systems increasingly influence specification decisions, especially in commercial and industrial contexts.
Together, these forces create a market environment where compliance, material resilience, and technological differentiation converge. The report evaluates each force through a practical lens, linking regulatory requirements and material dependencies to segment behavior, competitive readiness, and near-term execution risk.
What the Study Delivers: From Macro Signals to Operational Playbooks
PW Consulting’s Worldwide Classified Circuit Breaker Market research is structured to support decision-making at multiple levels of the organization. At the strategic level, the study provides a forecast framework that traces revenue evolution from 2026 through 2032, anchored by historical data from 2020 to 2025. This enables leadership teams to benchmark growth expectations, stress-test assumptions, and align investment timing with market momentum. The analysis is presented in USD millions and calibrated to a 6.0 percent compound annual growth rate across the forecast period, offering a consistent reference point for planning and scenario development.
At the tactical level, the report examines segmentation dynamics across type, application, and region. Rather than isolating splits as static figures, it contextualizes how miniature and molded case circuit breakers perform against distinct demand drivers, how residential renovation, commercial retrofitting, and industrial maintenance shape purchasing behavior, and how regional demand profiles influence channel design, fulfillment strategy, and competitive exposure. This approach helps procurement, sales, and product teams prioritize where compatibility, pricing, and availability most directly affect win rates and share capture.
The competitive section goes beyond corporate descriptions to evaluate positioning logic. It assesses how broad-line compatibility, replacement-focused portfolios, industrial-grade portfolios, and regional assembly or sourcing strategies shape market access. It also incorporates recent developments—including trade show showcases, prototype disclosures, and local assembly announcements—to illustrate how product roadmaps and supply chain moves are shifting the competitive frontier. For executives tracking partnership opportunities, substitution threats, or regional expansion options, this analysis provides a structured basis for evaluating where value is created and defended.
Equally important, the study integrates industry context into the analytical narrative. Regulatory interchangeability standards, material input dependencies, and macro-driven innovation trends are treated not as background commentary but as active variables that influence demand elasticity, margin structure, and execution feasibility. The goal is to give organizations a practical reading of the market environment, not just a tally of sizes and shares.
Why This Intelligence Matters for 2026 Decision-Making
The 2026 decision environment calls for clarity on three questions: where demand is structurally growing, how competitive advantages are being constructed, and which external forces will alter execution outcomes. The classified circuit breaker market sits at the intersection of replacement economics, safety compliance, loadcenter compatibility, and emerging digital functionality. In such a market, the difference between a reactive strategy and a proactive one often comes down to the quality of the underlying intelligence.
Organizations evaluating capacity expansion, product portfolio adjustments, channel investments, or regional sourcing moves need more than headline growth numbers. They need to understand how type and application dynamics interact with regional demand, how compatibility breadth translates into competitive resilience, and how regulatory and material factors shape cost and risk. They also need to anticipate where digital and smart breaker innovations will begin to influence specification behavior, particularly in commercial and industrial segments.
This study is built to support those judgments. It combines historical grounding, forecast discipline, segmentation context, competitive evaluation, and industry dynamics into a single analytical framework. For executives, that means faster alignment on strategic priorities, sharper allocation decisions, and a more defensible basis for market entry, expansion, or defensive positioning.
Accessing the Full Market Intelligence
The preview above outlines the strategic architecture of the market and the analytical value embedded in the full research. However, the complete study contains the detailed segmentation breakdowns, regional revenue distributions, application-level demand patterns, company-specific positioning assessments, and forecast tables required to operationalize strategy. Those granular insights are essential for procurement planning, product roadmap prioritization, competitive benchmarking, and investment justification.
To obtain the full Worldwide Classified Circuit Breaker Market report and access the complete dataset behind this analysis, please visit the source page where the study is available for review and acquisition. The full report provides the depth needed to convert market intelligence into executable 2026 strategy—whether the objective is to strengthen compatibility-driven positioning, optimize regional supply, assess substitution risk, or align product development with emerging demand signals.
For detailed analysis of this topic, please visit the official page: Worldwide Classified Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Slaked Lime Market to Reach $9B by 2032, Driven by 4.25% CAGR
By PW Consulting, 2026-09-17
Navigating the Slaked Lime Sector in 2026: Strategic Imperatives from PW Consulting's Global Outlook
The global slaked lime market stands at a critical intersection of regulatory pressure, infrastructure renewal, and energy-driven cost volatility. As industrial operators and municipal authorities alike confront tightening emissions standards and aging water treatment networks, the demand for high-purity calcium hydroxide has evolved from a commodity consideration into a strategic supply chain priority. PW Consulting's latest Worldwide Slaked Lime Market report offers decision-makers a comprehensive, data-grounded lens into this transformation, mapping historical trajectories, projecting medium-term growth, and dissecting the competitive and operational forces that will define profitability through 2032.
For executives operating in construction, environmental services, chemical manufacturing, or public utilities, the 2026–2032 forecast period demands more than incremental planning. It requires a clear understanding of where value is concentrating, how feedstock economics are reshaping margin structures, and which regional demand centers will absorb capacity expansion. This overview distills the analytical architecture of the full study, illustrating how the report translates macro trends into actionable intelligence while preserving detailed quantitative breakdowns for subscribers who require precision in their strategic modeling.
The Macro Trajectory: Growth, Volatility, and Structural Shifts
The global slaked lime market has demonstrated resilient expansion over the past half-decade, progressing from approximately USD 5,450.2 million in 2020 to an estimated USD 6,745.5 million in 2025. This historical arc reflects a compound trajectory shaped by post-pandemic infrastructure stimulus, sustained environmental compliance spending, and the gradual recovery of industrial processing volumes across multiple regions. Our baseline projection extends this momentum into a forecast window running through 2032, with the market advancing toward the USD 9 billion threshold as construction cycles mature, water and wastewater treatment mandates intensify, and flue gas desulfurization programs scale in high-emission economies.
The projected compound annual growth rate of 4.25 percent through 2032 may appear measured at first glance, but it understates the operational complexity beneath the headline figure. Medium-term growth is neither uniform nor automatic; it is being filtered through energy pricing dynamics, freight cost variability, and divergent regulatory timelines across jurisdictions. Forecasts for individual years between 2026 and 2032 reveal periods of acceleration followed by modest contractions, underscoring how capacity timing, feedstock availability, and demand-side project pipelines interact to create a non-linear revenue path. The full report unpacks these year-by-year inflection points, enabling planners to align procurement calendars, capex commitments, and product mix decisions with realistic volume expectations rather than smoothed averages.
Understanding the absolute revenue scale of the market is essential, but so is recognizing where concentration lies and where fragmentation persists. The total addressable opportunity across all forms, applications, and regions continues to expand, yet the distribution of that opportunity is highly uneven. Decision-makers who rely on aggregate growth rates without understanding the underlying structural drivers risk misallocating resources toward segments with limited margin expansion or constrained capacity absorption.
Regulatory Tailwinds and Supply-Side Constraints
Environmental regulation remains the most persistent catalyst for slaked lime demand. Stringent pollution control requirements across the United States, China, and India continue to drive procurement for hydrated lime in flue gas treatment and water and wastewater applications. As industrial emitters face tighter sulfur oxide, particulate, and heavy metal discharge limits, the consumption of high-purity slaked lime in desulfurization scrubbing systems and neutralization processes has become a compliance necessity rather than an optional upgrade. This regulatory floor provides a degree of demand certainty that insulates the market from cyclical downturns in discretionary construction or industrial processing.
Yet the supply side of the equation has grown increasingly complex. Lime kilns are inherently energy-intensive, requiring between 4.5 and 10 megajoules of fuel per kilogram of quicklime produced. Surges in natural gas and fuel oil prices accordingly translate directly into higher calcination costs, compressing margins for producers who cannot pass through cost increases or who operate with inflexible contract structures. In early 2026, quicklime feedstock pricing reflected significant geographic divergence, with benchmarks reported at approximately USD 156 per metric ton in China, USD 170 per metric ton in the Netherlands, and USD 128 per metric ton in the United States. These differentials influence downstream slaked lime economics, shaping regional competitiveness, import-export dynamics, and the viability of localized versus centralized production models.
Compounding these cost pressures, geopolitical tensions in early 2026 disrupted energy flows and logistics corridors, pushing freight rates higher by roughly 15 to 25 percent and adding surcharges to lime-related products. For buyers and sellers alike, the result has been a market where delivery reliability, regional inventory positioning, and contract hedging have become as strategically important as unit pricing. The report examines how these energy, logistics, and regulatory layers interact, providing a framework for evaluating risk exposure across procurement geographies and supply routes.
Regional and Application Dynamics: Where Demand Converges
Demand for slaked lime is distributed across a diverse set of end-use environments, each with distinct volume drivers, specification requirements, and procurement cycles. At a high level, the market's application footprint spans water and wastewater treatment, environmental protection through flue gas desulfurization, construction and infrastructure, chemical and industrial processing, and agriculture or soil treatment. The relative weight of these segments reflects broader economic and policy priorities: environmental compliance and municipal water security consistently anchor baseline demand, while construction activity and industrial processing volumes introduce cyclical sensitivity.
Regionally, the market's footprint is anchored by the Asia Pacific region, followed by Europe and North America, with Latin America and the Middle East and Africa representing additional but comparatively smaller demand pools. This distribution is not static. Shifts in municipal infrastructure investment, industrial relocation patterns, and the pace of environmental regulation implementation are gradually reweighting demand geography. Capacity additions in one region can alter trade flows, while localized feedstock availability and energy cost structures determine which production hubs remain competitive over time.
The full report provides granular segmentation that maps these regional and application dynamics in detail, allowing readers to assess which end-use categories are expanding most rapidly, how form preferences vary by region, and where regulatory or infrastructure projects are likely to generate near-term procurement spikes. Access to this level of segmentation is essential for companies evaluating market entry, capacity allocation, or product specialization strategies.
The Competitive Landscape: Scale, Focus, and Recent Moves
The slaked lime sector features a mix of globally integrated producers and regionally focused manufacturers, with consolidated players commanding significant but not overwhelming market share. The top three competitors account for approximately 18.4 percent of total market revenue, while the top five reach roughly 26.15 percent. This concentration profile indicates a market where scale matters for cost efficiency and distribution reach, yet where regional specialists and niche-grade producers retain meaningful positioning through localized service, product customization, and specialized application expertise.
Several established players illustrate the strategic directions shaping the competitive field. Carmeuse, headquartered in Belgium, operates as a global leader in lime products spanning high-calcium and dolomitic hydrated lime for steelmaking, environmental, construction, and chemical applications, with production facilities distributed across North America, Europe, and Asia. Lhoist Group, also based in Belgium, operates in more than 25 countries and supplies high-purity grades for water treatment, flue gas desulfurization, construction, and industrial uses, maintaining significant global production volumes. Graymont Limited, headquartered in Canada, has reinforced its North American and Asia-Pacific presence by focusing on construction, environmental, and industrial markets while pursuing capacity additions through acquisitions.
In the United States, Mississippi Lime Company stands as a key manufacturer of high-calcium quicklime and hydrated lime for chemical, industrial, environmental, and construction sectors, operating multiple plants with an emphasis on high-purity and specialty grades. United States Lime & Minerals, Inc. produces quicklime and hydrated lime from limestone quarries for construction, metals, environmental, oil and gas, and agriculture applications across multiple states. Complementary producers such as Nordkalk in Finland, Linwood Mining & Minerals Corporation, Cheney Lime & Cement Company, Pete Lien & Sons, Inc., Cape Lime in South Africa, Sigma Minerals Ltd in India, Valley Minerals LLC, Cornish Lime in the United Kingdom, Brookville Manufacturing in Canada, and Minerals Technologies Inc. in the United States further enrich the competitive fabric, each contributing regional depth, specialized grades, or application-specific capabilities.
Recent corporate activity underscores how companies are positioning for the 2026–2032 cycle. In February 2026, Lhoist Group commissioned an expanded hydrated lime production facility in North America to support growing demand from water treatment and flue gas desulfurization markets. Earlier, in January 2026, Graymont Limited announced a strategic partnership with a leading municipal water authority for the long-term supply of high-purity hydrated lime supporting water treatment plant upgrades, following its September 2025 acquisition of a lime processing facility in Malaysia that added significant quicklime and hydrated lime production capacity. In January 2025, Mississippi Lime Company committed to constructing a state-of-the-art sustainable kiln at its Bonne Terre, Missouri facility, signaling the industry's increasing attention to energy efficiency and environmental performance as competitive differentiators.
Worldwide Slaked Lime Market
These developments reflect a broader pattern: producers are aligning capacity investments and partnership structures with demand visibility in water and environmental applications, while simultaneously pursuing operational efficiencies that mitigate energy cost exposure. The report analyzes these moves not as isolated announcements but as indicators of how competitive advantage is being redefined through regional capacity timing, feedstock integration, and application specialization.
What the Full Report Delivers
PW Consulting's Worldwide Slaked Lime Market study is structured to support multiple layers of strategic decision-making. Beyond the macro revenue trajectory and forecast horizon, the report provides a detailed segmentation architecture covering product forms, end-use applications, and geographic markets. This structure enables readers to evaluate not just how large the market is, but how value is distributed across powdered slaked lime, slurry or milk of lime, and granular slaked lime; across environmental, construction, water treatment, chemical, and agricultural applications; and across the regional demand centers that shape procurement and logistics strategies.
The competitive analysis extends beyond corporate profiles to assess positioning, capacity footprints, and strategic timing. Readers gain insight into how leading producers are balancing scale with specialization, how recent facility expansions and acquisitions alter regional supply dynamics, and where fragmentation still creates opportunities for focused entrants or niche-grade suppliers. The inclusion of recent industry developments, from commissioning events to partnership announcements and sustainable production commitments, anchors the competitive assessment in real-time operational realities rather than static positioning maps.
Equally important, the study integrates supply-side dynamics that directly affect commercial planning. Energy intensity, feedstock pricing divergence, freight cost volatility, and regulatory implementation timelines are examined as interconnected variables rather than isolated headwinds. This integrated perspective helps procurement leaders, production planners, and market strategists evaluate where cost pressure is structural versus cyclical, where contractual flexibility can protect margins, and where capacity timing can create temporary windows of advantage or risk.
Worldwide Hydrated Lime Market
The full report also includes historical data spanning 2020 through the base year of 2025, providing a calibrated baseline against which forecasts can be tested. This historical context is essential for validating trend assumptions, understanding the magnitude of post-stimulus recoveries, and identifying whether current growth patterns reflect durable demand expansion or temporary cyclical rebounds.
Strategic Takeaways for 2026 Decision-Makers
For executives navigating the slaked lime sector in 2026 and beyond, several strategic imperatives emerge from the study's analytical framework:
- Recognize that regulatory-driven demand provides a durable baseline but does not eliminate volatility in construction, industrial processing, and freight-exposed segments.
- Model procurement and production decisions against year-by-year forecast variation rather than relying on smoothed long-term growth rates, especially where energy and logistics costs can shift margin profiles quickly.
- Assess regional competitiveness through the combined lens of feedstock pricing, energy cost structures, and freight exposure, since these variables increasingly determine which production hubs can compete on total delivered cost.
- Evaluate partnership and capacity strategies against visible demand pipelines in water treatment, flue gas desulfurization, and infrastructure projects, where multi-year procurement visibility can justify targeted capacity investments or long-term supply agreements.
- Monitor competitive moves not only by announced capacity additions but by the timing of commissioning, the specificity of application focus, and the operational efficiency investments that will determine cost leadership over the forecast period.
The slaked lime market is no longer a straightforward commodity play. It is a sector where regulatory mandates, energy economics, logistics constraints, and regional infrastructure priorities converge to shape both demand and competitive positioning. PW Consulting's Worldwide Slaked Lime Market report equips stakeholders with the analytical depth required to navigate that complexity, translating broad market trajectories into segment-level insights, competitive intelligence, and supply-side context that can be directly incorporated into commercial and operational planning.
For organizations that require precise segmentation data, region-specific demand breakdowns, form-level revenue splits, and detailed competitor benchmarking, the complete study provides the full quantitative architecture behind these strategic observations. Access to the complete dataset and analysis ensures that planning assumptions are grounded in validated market structure rather than aggregated approximations, enabling sharper execution across procurement, capacity, and market development decisions throughout the 2026–2032 forecast window.
For detailed analysis of this topic, please visit the official page: Worldwide Slaked Lime Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Heated Windshield Market Hits $1.2B in 2025, Projected 14.12% CAGR to $3B by 2032
By PW Consulting, 2026-09-17
Strategic Intelligence Brief: Electrically Heated Windshields in the EV Era
The transition to electric mobility has fundamentally altered the thermal management priorities of original equipment manufacturers. Where internal combustion engines offered abundant waste heat for cabin and glass de-icing, battery electric vehicles demand precise, energy-efficient solutions that preserve driving range without compromising safety or driver comfort. Electrically heated windshields have emerged as a critical technology at this intersection, and our latest market research provides a comprehensive, data-driven roadmap for stakeholders navigating this rapidly evolving landscape.
Market Trajectory and Structural Growth Signals
The global market for electrically heated windshields has demonstrated resilient, high-velocity expansion over the past half-decade, scaling from approximately 612.45 million USD in 2020 to a projected 1.207 billion USD by 2025. This trajectory reflects not merely incremental adoption but a structural shift in vehicle architecture, where cabin thermal loads are increasingly decoupled from centralized HVAC systems in favor of localized, intelligent heating elements. Looking ahead, the market is forecast to continue its ascent through 2032, underpinned by a compound annual growth rate of 14.12 percent. By the close of our forecast window, industry revenues are expected to surpass 3 billion USD, signaling a mature but still accelerating commercial phase.
This growth is not uniform across all vehicle segments or technological approaches. The data reveals a clear preference among manufacturers for solutions that minimize parasitic energy drain, accelerate defrost cycles, and integrate seamlessly with advanced driver assistance systems. The shift from conventional 12-volt heating circuits to higher-voltage architectures has further accelerated adoption, enabling manufacturers to deliver rapid thermal performance while preserving the high-voltage battery for propulsion. Understanding where value is being captured, which technological pathways are gaining share, and how regional supply chains are aligning requires a granular view that goes well beyond headline figures. Our report dissects these layers systematically, providing decision-makers with the granularity needed to allocate capital, shape sourcing strategies, and anticipate competitive displacement.
Report Architecture and Operational Content
Our research is structured to bridge strategic oversight with tactical execution. Rather than offering a static snapshot, the analysis maps the interplay between material science, vehicle architecture, regulatory frameworks, and consumer expectations, translating these forces into actionable commercial intelligence. Key deliverable categories include:
- A longitudinal market sizing exercise covering the historical baseline from 2020 through the base year of 2025, alongside a forward-looking forecast extending to 2032, with explicit modeling of demand drivers, adoption curves, and price dynamics.
- A technology segmentation deep-dive comparing conductive coating approaches with fine-wire heating architectures, evaluating performance trade-offs in defrost speed, energy consumption, optical clarity, and integration complexity with ADAS sensor zones.
- A vehicle-type breakdown isolating demand patterns across battery electric and plug-in hybrid platforms, highlighting how chassis electrical architecture, battery capacity, and regional cold-weather usage profiles shape procurement decisions.
- A competitive landscape assessment profiling the strategic positioning, flagship product capabilities, and recent development milestones of leading glass manufacturers and technology specialists.
- A regulatory and compliance overview detailing the safety glazing standards, optical and impact-resistance requirements, and electrical safety mandates that govern heated windshield deployment across major automotive markets.
- A raw material and supply chain lens examining interlayer material dynamics, cost volatility signals, and how material innovation translates into energy savings and acoustic performance for electric vehicles.
Each section is designed to feed directly into product roadmap planning, supplier negotiations, and market-entry evaluations. By anchoring findings in verifiable development trajectories and quantifiable adoption metrics, the report equips strategy, procurement, and engineering leadership with a unified evidence base.
Competitive Landscape and Strategic Positioning
The competitive architecture of the electrically heated windshield market is characterized by a concentrated group of established glass manufacturers alongside specialized technology innovators that are redefining defrost performance benchmarks. Our analysis segments these players by their core technological philosophies, partnership ecosystems, and recent capability demonstrations, revealing distinct strategic postures that will shape procurement dynamics through the forecast period.
Structural Concentration and Incumbent Capabilities
Market concentration remains notable, with the top three participants accounting for a substantial share of total revenue and the top five firms extending that footprint further. This concentration reflects the capital intensity of automotive glass manufacturing, the certification burdens associated with safety glazing standards, and the long qualification cycles inherent in vehicle program development. Within this environment, incumbents have invested heavily in dual-track technology portfolios that address both performance and efficiency imperatives.
AGC Inc. has advanced a HeatControl Windshield built around conductive coating technology for silent electrical de-icing and defogging, while simultaneously offering a Heated Wire Windshield that embeds superfine wires for rapid defrosting. Both product lines are explicitly optimized for electric vehicle thermal management and energy efficiency, positioning AGC to serve automakers seeking either seamless optical integration or high-speed heat delivery depending on vehicle architecture.
Pilkington, operating under the NSG Group, supplies wire-heated windshields engineered for fast defrosting and defogging, with heating elements designed to be compatible with advanced driver assistance systems. Its value proposition emphasizes range extension in cold conditions, directly addressing the winter efficiency penalty that remains a consumer concern for electric vehicle adoption.
Fuyao Glass Industry Group has focused on tungsten-wire heating elements embedded within the polyvinyl butyral interlayer, with wire specifications calibrated for reliable frost, fog, and ice melting. Its offering includes targeted heating zones for wiper, sensor, and camera areas, aligning with the increasing reliance on forward-facing optical systems in electric vehicle platforms.
Saint-Gobain Sekurit has developed the ClimaCoat heated windshield, which employs an invisible conductive coating for de-icing and de-misting while combining heating with heat reflection for all-weather performance. This approach underscores a broader trend among large glass manufacturers to bundle thermal, acoustic, and solar-control functions into integrated glazing solutions that simplify vehicle packaging.
Technology Specialists and Architecture Innovation
Beyond the established glass manufacturers, a set of technology-focused players is reshaping performance expectations through alternative thermal delivery methods. Betterfrost Technologies specializes in pulsed electro-thermal deicing systems that achieve defrost cycles in approximately 60 to 75 seconds while consuming up to 95 percent less energy than conventional HVAC defrosting. This pulsed approach is particularly compelling for electric vehicle winter range preservation, and the company has been actively engaging automakers and Tier 1 suppliers for both electric vehicle and commercial applications, with recent testing activity highlighting the practical readiness of its system.
Hyundai Motor Group, through its Genesis brand, has pursued an architecture-level innovation with 48-volt metal-coated heated glass built on a multi-layer transparent coating. Testing on Electrified GV70 and GV60 platforms demonstrated clearance of 100 percent frost in roughly five minutes, compared with the fifteen-minute timeline of conventional systems, while consuming approximately 10 percent less power. The group has also publicized solar reflection properties as part of the system’s broader efficiency rationale, and the demonstration has drawn attention to the role of 48-volt electrical architectures in reducing energy draw from the high-voltage battery relative to legacy 12-volt systems.
Electrically Heated Windshield for EV Market
These developments illustrate a market where technology differentiation is increasingly tied to energy economics, defrost speed, and ADAS compatibility rather than heating presence alone. Procurement teams evaluating supplier partnerships must therefore weigh not just glass quality and production capacity, but the electrical architecture compatibility, certification status, and integration roadmap of each heating approach.
Industry Dynamics Shaping Demand and Deployment
Several concurrent forces are accelerating the commercial relevance of electrically heated windshields and complicating the decision calculus for manufacturers and suppliers alike. A primary catalyst is the broader migration toward 48-volt electrical architectures in electric vehicles, which enables more efficient powering of heated glazing and reduces the energy penalty traditionally associated with cabin and glass heating. This architectural shift is lowering the barrier for integrating high-performance heated windshields without compromising propulsive range, and it is prompting vehicle programs to revisit thermal management specifications earlier in the design cycle.
On the materials side, the polyvinyl butyral interlayer remains the foundational lamination component for embedding heating wires or conductive coatings. Interlayer pricing dynamics have introduced a volatility variable into supply chain planning, with industry data indicating that export-grade PVB materials experienced year-on-year price movements in the 2025 period. At the same time, advanced interlayer formulations are increasingly marketed for their combined acoustic, thermal, and energy-saving properties, with some product data suggesting that integrated heating functions paired with optimized interlayer characteristics can support meaningful efficiency gains. This dual reality of cost fluctuation and performance optimization requires procurement strategies that balance price risk with specification value.
Regulatory expectations continue to anchor product development. Electrically heated windshields deployed in electric vehicles must comply with automotive safety glazing standards that enforce optical clarity, impact resistance, and electrical safety, while also supporting the integration of ADAS cameras and sensors. Compliance is not merely a minimum threshold; it increasingly functions as a differentiator in program approvals, particularly as heated zones must be coordinated with sensor fields of view and mounting locations. Our report maps these compliance dimensions across key markets, clarifying where certification pathways converge and where regional divergence creates planning complexity.
Strategic Value for 2026 Decision-Making
For organizations making capital allocation, supplier selection, and product planning decisions in 2026, the value of this research lies in its ability to convert macro momentum into operational clarity. The headline growth trajectory and structural drivers establish why the market matters; the segmentation, competitive profiling, and technology comparisons determine where advantage can be captured. Our analysis is designed to answer several decision-critical questions:
Heated Windshields Market
- Which technological pathways are gaining traction among vehicle programs targeting cold-climate markets, and what trade-offs do they present in energy consumption, defrost latency, and ADAS integration?
- How are leading glass manufacturers and technology specialists positioning themselves for the next wave of electric vehicle platforms, and where are the gaps that new entrants or partnership strategies can exploit?
- What supply chain and raw material dynamics should procurement teams monitor to mitigate cost volatility while preserving specification performance?
- How do regulatory and safety glazing requirements shape the commercialization timeline for heated windshield deployments across major automotive regions?
By addressing these questions with rigorously sourced data and forward-looking interpretation, the report enables strategy and engineering leaders to align product roadmaps with market reality, structure supplier negotiations with evidence rather than assumption, and anticipate the competitive implications of technology shifts before they become industry consensus.
Conclusion and Access to the Full Intelligence Package
Electrically heated windshields are no longer a comfort accessory; they are a functional component of electric vehicle energy management, safety compliance, and consumer acceptance in cold-weather markets. The convergence of advanced coating and wire technologies, 48-volt architecture adoption, evolving interlayer materials, and targeted defrost innovations has created a market in which differentiation is accelerating and competitive positioning is being redefined in real time. Our full report provides the complete segmentation data, regional breakdowns, technology comparisons, and company-level profiles required to translate these dynamics into precise strategic action. To access the detailed quantitative models, the full competitive matrix, and the scenario-based forecast supporting these insights, we invite you to review the complete Electrically Heated Windshield for EV Market research on our platform.
For detailed analysis of this topic, please visit the official page: Electrically Heated Windshield for EV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Towed Array Sonar Market to Hit $1.83B by 2032, Growing at 5.2% CAGR
By PW Consulting, 2026-09-17
Global Undercurrents: Strategic Insights into the Towed Array Sonar Market Through 2032
The undersea domain has become the defining theater of modern naval competition. As quiet submarines grow more sophisticated and unmanned underwater vehicles proliferate, navies worldwide are re-evaluating their anti-submarine warfare capabilities. At the heart of this shift lies towed array sonar technology, a critical sensor suite that extends acoustic detection ranges far beyond the hull of a ship or submarine. For defense contractors, procurement officers, and investors, understanding where this market is heading is no longer optional. PW Consulting presents our comprehensive Worldwide Towed Array Sonar System Market analysis, designed to equip decision-makers with the intelligence needed to navigate a rapidly evolving landscape from 2026 through 2032.
This introduction provides a strategic preview of the findings contained within our full report. It outlines the trajectory of the global market, the competitive forces shaping supply, and the geopolitical and industrial dynamics driving procurement. Our goal is to demonstrate the depth of analysis available while highlighting why detailed segmentation and forward-looking modeling are essential for capitalizing on emerging opportunities.
Market Trajectory and Growth Outlook
The global towed array sonar market has demonstrated resilient growth over the past half-decade, evolving from a specialized naval requirement into a broader strategic asset class. Our analysis covers historical performance from 2020 through 2025, with a detailed forecast extending to 2032. In 2025, the market established a baseline of 1,280 million USD, reflecting sustained investment in anti-submarine warfare modernization programs across major naval powers.
Looking ahead, the forecast period reveals an accelerating expansion trajectory. Revenue is projected to reach 1,336.9 million USD in 2026, moderating slightly before climbing steadily through the end of the decade. By 2032, the market is anticipated to reach 1,825.23 million USD. This growth translates to a compound annual growth rate of 5.2 percent over the forecast window, driven by a combination of fleet renewal cycles, technological upgrades, and escalating undersea threats.
The historical data underscores a pattern of organic expansion punctuated by procurement spikes. Growth from 2020 to 2025 reflects the post-pandemic recovery of defense budgets and the prioritization of undersea surveillance assets. Notably, revenue growth is expected to gain momentum after 2027, suggesting that program approvals and major contract awards initiated in the mid-2020s will begin materializing in reported revenues toward the end of the decade. Decision-makers evaluating entry points or expansion strategies must account for this lag between procurement announcements and realized market revenue.
Strategic Segmentation and Application Realities
Effective market strategy requires a clear understanding of how demand is distributed across technology types, platforms, and geographic theaters. Our report dissects the market into granular segments that reveal where the highest-value opportunities reside.
Technology Types and Platform Integration
The market is bifurcated primarily by sensor architecture, with passive towed arrays commanding a larger revenue share than active systems. Passive arrays remain the cornerstone of long-range detection, favored for their ability to listen without revealing the host platform's position. Active towed arrays, while smaller in current revenue terms, are gaining traction in scenarios requiring precise target localization and tracking in high-clutter environments. Both technologies are increasingly integrated into multi-function suites that combine variable depth capabilities with advanced signal processing.
Platform adoption follows a distinct hierarchy. Surface warships represent the largest application segment, driven by the broad deployment of frigate, destroyer, and cruiser fleets equipped with variable-depth and towed array systems for open-ocean anti-submarine warfare. Submarines constitute the second-largest application, with towed arrays serving as essential complements to hull-mounted sonars on attack and ballistic missile submarines. A third, rapidly emerging segment is unmanned underwater vehicles. Though currently the smallest in revenue terms, this segment reflects a strategic pivot toward distributed sensing networks and autonomous reconnaissance, areas where lightweight towed array adaptations are beginning to appear in prototype and early-production configurations.
Geographic Demand Distribution
Demand is not uniformly distributed across global theaters. North America remains the largest regional market, reflecting the United States Navy's extensive modernization programs and the deep integration of towed array systems across submarine and surface combatant fleets. Europe follows as a significant market, shaped by NATO interoperability requirements and the procurement cycles of major naval powers. The Asia Pacific region represents a substantial and growing share of demand, fueled by security dynamics in key maritime corridors and the region's accelerating naval procurement. The Rest of World segment, while smaller in absolute terms, includes strategic procurements by allied nations seeking to enhance their anti-submarine capabilities in coordination with major defense partners.
For prospective suppliers and investors, the geographic breakdown is not merely a snapshot of current revenue. It reflects where procurement pipelines are deepest, where upgrade cycles are most active, and where export opportunities are constrained or enabled by regional policy frameworks. Our full report maps these dynamics in detail, providing the regional intelligence necessary to align sales strategies with actual demand centers.
Worldwide Towed Array Sonar System Market
Competitive Landscape: Leaders, Dynamics, and Strategic Positioning
The towed array sonar market is characterized by a concentrated supplier base, with a handful of established defense primes and specialized maritime technology firms commanding the majority of revenue. Our analysis indicates a heavily consolidated landscape, with the top three players accounting for 64.5 percent of market revenue and the top five representing 82.2 percent. This concentration reflects the high barriers to entry created by complex integration requirements, long certification timelines, and the necessity of deep relationships with naval procurement authorities.
Worldwide Towed Sonar Market
Several firms define the competitive frontier. L3Harris Technologies, based in Melbourne, Florida, has reinforced its position through the integration of advanced towed array suites such as the AN/SQQ-89 and thin-line arrays like the TB-29 and TB-37 for US Navy submarines and surface ships. In October 2025, the company secured a US Department of Defense contract for TB-37 Multi-Function Towed Array upgrades, signaling continued investment in next-generation signal processing and sensor capability. Thales Group, headquartered in Paris, supplies the CAPTAS variable depth sonar and towed array systems such as SLASM for anti-submarine warfare on frigates and destroyers. Its June 2025 delivery of the CAPTAS-4 towed array sonar to the Royal Canadian Navy for Halifax-class frigate upgrades demonstrates the company's ability to support both new construction and life-extension programs across allied fleets.
Lockheed Martin Corporation, based in Bethesda, Maryland, continues to develop and integrate towed array sonars including the AN/BQQ-10 for Virginia-class submarines and SURTASS/Low Frequency Active systems. A key integration milestone was achieved in November 2024 with the completion of AN/BQQ-10 towed array integration on a Block V Virginia-class submarine, underscoring the company's role in next-generation submarine sensor suites. Atlas Elektronik, part of ThyssenKrupp Marine Systems and headquartered in Bremen, Germany, manufactures low-frequency towed array sonars and systems tailored for Type 212 submarines, maintaining a strong European supply footprint. Leonardo S.p.A., based in Rome, offers towered array systems such as BlackHole and W-ASS for Italian Navy frigates and international export markets, while Ultra Maritime, headquartered in Dartmouth, UK, produces the Sea Spear towed array sonar and has supported Type 23 frigate upgrades to bolster Royal Navy anti-submarine warfare capabilities.
The competitive dynamics extend beyond product portfolios. Recent contract awards, delivery milestones, and integration achievements reveal which firms are successfully translating development work into fielded systems. Our report evaluates each competitor's strategic positioning, including their strength in specific technology segments, geographic reach, and the durability of their contractual relationships with major naval customers. For organizations considering partnerships, acquisitions, or competitive entry, this competitor intelligence is critical to understanding where market share is being won and lost.
Industry Dynamics: Supply Constraints, Regulation, and Geopolitical Forces
Market growth does not occur in a vacuum. Several structural forces are reshaping the supply environment, cost structures, and the pace at which new systems can be fielded.
Material Constraints and Cost Pressures
The production of sonar transducers relies heavily on PZT-based piezoelectric ceramics, which serve as the core sensing elements in towed array systems. Recent supply-side developments have introduced cost pressures. Rare earth supply constraints linked to Chinese export restrictions have driven an 8 percent price increase in PZT-based piezoelectric ceramics, according to mineral commodity data from January 2026. This escalation affects not only raw material costs but also the broader economics of sonar system production, particularly for manufacturers operating on fixed-price contracts or seeking to maintain competitive pricing in export markets. Understanding how suppliers are mitigating these cost pressures through material substitution, inventory strategies, or supplier diversification is essential for evaluating long-term profitability and contract risk.
Export Controls and Technology Transfer Restrictions
The transfer of towed array sonar technology is heavily influenced by regulatory frameworks governing defense trade. ITAR and the Wassenaar Arrangement impose strict export controls on sonar technologies, limiting technology transfers to non-NATO allies and complicating cross-border collaboration on development programs. These restrictions shape who can buy, who can build, and under what conditions systems can be integrated across allied supply chains. For commercial players, this means that market access is often determined as much by regulatory alignment as by technical capability. Our report examines how these controls affect regional market dynamics and where exceptions or allied cooperation frameworks create viable pathways for technology sharing and joint development.
Geopolitical Drivers and Alliance Frameworks
Geopolitical tensions are among the most powerful accelerants of demand. The AUKUS Pillar 2 agreement, announced in September 2024, has accelerated shared development of advanced anti-submarine warfare sonar technologies among the United States, United Kingdom, and Australia. This trilateral framework is fostering collaborative research, interoperability standards, and procurement alignment that benefit suppliers positioned to participate in joint programs. Simultaneously, security tensions in the South China Sea have driven Indo-Pacific nations to procure towed array sonars for anti-submarine warfare fleet upgrades, according to arms transfer data from December 2025. These regional pressures are expanding the addressable market beyond traditional NATO procurement cycles and creating new demand centers in Asia.
Integration with Unmanned and Distributed Systems
Beyond traditional platform integration, the market is witnessing a strategic shift toward distributed sensing. Towed array technology is being adapted and miniaturized for use with unmanned underwater vehicles, expanding the scope of where and how acoustic sensing can be deployed. This transition introduces new requirements around weight, power consumption, autonomous deployment, and data fusion, creating both challenges and opportunities for suppliers. Firms that can deliver compatible, scalable solutions for unmanned platforms will be positioned to capture growth in an application segment that, while currently small, is expected to expand as navy doctrines increasingly embrace autonomous reconnaissance networks.
Strategic Value for 2026 Decision-Making
For executives, procurement leaders, and investors evaluating the towed array sonar sector in 2026, the decisions made today will determine competitive positioning for the remainder of the decade. The market is entering a phase where growth is no longer linear but shaped by intersecting factors: fleet modernization timelines, material cost volatility, export control frameworks, alliance-driven R&D collaboration, and the emergence of unmanned platforms. A superficial understanding of market size and growth rate is insufficient to guide strategy. What is needed is detailed segmentation that reveals where revenue is concentrated, which applications are expanding fastest, which regions present the most viable export or partnership opportunities, and which competitors are securing the contracts that will define market share through 2032.
Our full Worldwide Towed Array Sonar System Market report delivers this depth. It combines macro-level trend analysis with actionable segmentation, competitor profiling, regulatory and supply chain mapping, and forward-looking scenario modeling. The report is designed to support concrete decisions: where to allocate sales and marketing resources, which technology segments to prioritize for R&D or acquisition, how to assess competitor moves in real time, and how to structure bids in a market where cost pressures and regulatory barriers can erode margins if not properly accounted for.
The preview provided here captures the structure and analytical rigor of the full study, but the complete picture requires access to the detailed data, segment breakdowns, regional demand models, and competitive intelligence compiled across hundreds of sources and validated through primary research. PW Consulting's analysis is built to serve as a strategic asset for organizations that need more than general market awareness. It is designed to provide the precision needed to act with confidence in a market where the difference between informed positioning and reactive decision-making can define long-term success.
For those committed to understanding the full scope of opportunity and risk in the towed array sonar market, the complete report offers the granularity and forward-looking insight necessary to translate market dynamics into strategic advantage. We invite you to explore the full study, where every segment, competitor profile, and dynamic driver is unpacked to support the decisions that will shape your position in the market through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Towed Array Sonar System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Baby Monitors Market Hits $1.85B in 2025, 8.12% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide Multifunction Baby Monitors Market
The global landscape for infant care technology is shifting from simple surveillance to comprehensive health and wellness ecosystems. As parents increasingly demand devices that offer more than just video feeds, the multifunction baby monitor sector has emerged as a critical battleground for consumer electronics firms, health tech startups, and established legacy brands. At PW Consulting, we have synthesized extensive primary and secondary research to produce our latest Worldwide Multifunction Baby Monitors Market study. This document serves as a strategic overview for executives, investors, and product leaders who need to navigate the complexities of the 2026-2032 forecast period with confidence.
Understanding the trajectory of this market requires more than just observing current sales figures. It demands a nuanced grasp of how technological convergence, regulatory pressures, and supply chain dynamics interact to shape revenue potential. Our latest research provides the framework necessary to make informed decisions in an environment characterized by rapid innovation and volatile component costs. This article outlines the strategic value of our findings, highlighting the macro-economic currents and competitive pressures that will define the industry over the next seven years.
Macro-Economic Trajectory and Growth Fundamentals
The financial scale of the multifunction baby monitors market underscores its significance as a high-growth vertical within the broader consumer electronics and health tech sectors. Our analysis establishes a robust baseline rooted in historical performance data spanning from 2020 through 2025. During this historical window, the market demonstrated consistent resilience and expansion, evolving from a valuation of approximately 1,260.4 million USD in 2020 to an estimated 1,850.25 million USD by 2025. This historical growth pattern reflects a steady adoption curve driven by increasing disposable incomes in key regions and a heightened parental focus on infant safety and sleep quality.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, albeit with evolving drivers. The market is projected to reach a valuation of roughly 1,991.97 million USD in 2026, climbing steadily to exceed 3,195.75 million USD by 2032. This expansion corresponds to a Compound Annual Growth Rate (CAGR) of 8.12 percent over the forecast horizon. Such growth rates indicate that the sector is outpacing many traditional consumer electronics categories, fueled by the integration of artificial intelligence, advanced sensor technology, and connectivity features that transform passive monitors into active health management tools.
However, revenue projections are only one piece of the puzzle. The strategic value for decision-makers lies in understanding the volume and value dynamics behind these figures. Our research dissects the factors contributing to this upward trajectory, including the premiumization of hardware, the subscription potential of accompanying apps, and the replacement cycles of older non-connected devices. By analyzing these underlying drivers, stakeholders can better anticipate shifts in consumer willingness to pay for advanced features such as breathing tracking, temperature sensing, and AI-enabled alerts.
Product Convergence and Technological Differentiation
The definition of a baby monitor has fundamentally changed. The market is no longer segmented simply by video versus audio; it is now defined by the depth of functionality integrated into a single unit. Our report categorizes the landscape into distinct product archetypes that reflect this convergence. Smart Wi-Fi Monitors represent the largest share of value generation, leveraging connectivity to offer remote viewing, cloud storage, and seamless integration with smart home ecosystems. These devices are increasingly becoming the hub for nursery monitoring, incorporating features that extend beyond basic observation.
Parallel to the smart video category is the growing prominence of Wearable Health Tracking Monitors. This segment has gained traction due to advancements in sensor miniaturization and battery life, allowing for contactless or minimal-contact health monitoring such as heart rate and oxygen level tracking. The convergence of video and wearable capabilities is particularly notable in high-end offerings where parents seek redundancy and comprehensive data. Meanwhile, Non-Wi-Fi Digital Monitors maintain a presence in the market, appealing to consumers with specific privacy concerns or those in regions with inconsistent internet infrastructure, though their growth trajectory differs significantly from the connected counterparts.
Technological differentiation is becoming the primary lever for competition. Features such as computer vision for breathing motion tracking, AI-driven alerts for rollover or face-covering risks, and environmental sensing for temperature and humidity are moving from niche innovations to expected standards in the premium tier. Our study details how these features impact unit economics, production complexity, and perceived value. For product managers, understanding the cost-benefit analysis of integrating these technologies is essential for positioning devices against competitors who may offer similar specs at different price points.
Regional Dynamics and Consumer Behavior
Geographical performance varies significantly across the global landscape, influenced by local purchasing power, regulatory environments, and the maturity of e-commerce channels. Our analysis covers key regions including North America, Europe, Asia Pacific, and the Rest of World. Each region presents a unique set of opportunities and challenges. In developed markets, demand is often driven by premiumization and the adoption of smart home ecosystems, whereas emerging markets may focus on entry-level digital solutions or affordability-driven smart options as connectivity improves.
Distribution channels also play a pivotal role in shaping market access and consumer reach. The shift towards Online Retail has accelerated, reflecting broader consumer behavior changes regarding electronics purchasing. Specialty Stores remain relevant for brands that rely on hands-on demonstration and expert advice, while Supermarkets and Hypermarkets offer volume opportunities for established, trusted brands. Our research evaluates the effectiveness of these channels in different regions, providing insights into where product visibility and conversion rates are highest. This granular understanding helps supply chain and sales teams optimize their distribution strategies to maximize market penetration without diluting brand equity.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of specialized health-tech innovators, large consumer electronics conglomerates, and agile entrants leveraging global supply chains. Market concentration indicates a moderately fragmented landscape, with the top three firms holding a combined share that leaves substantial room for disruption and consolidation. The top five players account for a significant portion of revenue, suggesting that scale and brand recognition are critical assets, yet mid-tier competitors continue to carve out niches through innovation.
Several key players define the current strategic context. Companies like Nanit and Owlet have positioned themselves at the intersection of video monitoring and health analytics. Nanit utilizes computer vision for breathing motion tracking and sleep insights, while Owlet has expanded into AI-enabled camera features paired with FDA-cleared wearable elements like the Dream Sock. These firms exemplify the trend towards multifunctionality where video, audio, and analytics are bundled to provide a holistic view of infant well-being.
Legacy and diversified electronics manufacturers also maintain a strong presence. VTech Communications offers video monitors with HD video, audio, and temperature monitoring, leveraging brand trust and distribution reach. Motorola's baby division provides connected options like the PIP1710 CONNECT, emphasizing reliability and connectivity. Meanwhile, brands like eufy and Cubo AI focus on smart features, with Cubo AI delivering AI rollover and face-cover alerts alongside environmental sensing. The presence of entities like Philips Avent highlights the interest of major healthcare-adjacent corporations in connected care portfolios, suggesting potential future convergence between consumer electronics and medical-grade monitoring concepts.
Other notable participants include Infant Optics, known for long-range transmission and interchangeable lenses; Momcozy and HelloBaby, which target value-conscious segments with 1080p video and multifunction features; and Miku, which emphasizes contactless breathing tracking. The list extends to companies like Angelcare, Dorel Industries through brands like Safety 1st, iBaby Labs, Lollipop, and even adaptable security hardware providers like Wyze Labs. This diverse array of competitors underscores the importance of clear value propositions. Our report provides detailed company profiles and strategic assessments of these players, analyzing their product roadmaps, geographical focus, and recent strategic moves.
Baby Monitoring System Market
Industry Dynamics: Regulatory, Supply Chain, and Operational Risks
Strategic planning in this sector must account for external forces that can materially impact operations and market access. Regulatory scrutiny is intensifying, particularly regarding safety standards for electronic devices used around infants. A notable example occurred in February 2026, when a significant recall was issued for approximately 81,800 units of a specific baby monitor model due to overheating and sparking hazards during charging. This event serves as a critical reminder of the reputational and financial risks associated with product safety failures. Our study incorporates these dynamics, offering guidance on compliance frameworks and quality assurance protocols necessary to mitigate such risks.
Supply chain stability remains another focal point. The market for camera modules, essential components for video-enabled multifunction monitors, was valued in the tens of billions of USD during the 2025-2026 period, with demand driven by consumer electronics including security and monitoring devices. This high demand can influence lead times and availability. Furthermore, component costs for microcontrollers and sensors have experienced upward pressure in early 2026, attributed to AI-driven demand and raw material fluctuations. Procurement teams need to be aware of these cost drivers as they impact margin structures and pricing strategies.
Geopolitical factors also introduce complexity. Export controls on advanced semiconductors and related manufacturing equipment continue to affect supply chains for chips used in smart Wi-Fi-enabled devices. Additionally, recent adjustments regarding imports of processed critical minerals and derivative products highlight national security concerns related to supply chain vulnerabilities. These macro-level developments can alter the cost and availability of critical components. Our research analyzes how these geopolitical and regulatory currents influence the manufacturing and distribution landscapes, helping stakeholders build more resilient supply chain strategies.
Real-Time Intelligence and Recent Market Developments
To remain actionable, market intelligence must be current. Our 2026 research incorporates the latest developments that signal shifting priorities and capabilities among key market participants. For instance, recent earnings and product updates from companies like Owlet highlight the rollout of AI-enabled camera features paired with wearable tracking, emphasizing enhanced multifunction monitoring beyond basic video. Such moves indicate a strategic pivot towards deeper data integration and health analytics.
Conversely, recent product recalls, such as the February 2026 action involving specific models sold through major retail channels, underscore the importance of rigorous safety testing and post-market surveillance. These events are not isolated incidents but part of a broader regulatory landscape that demands vigilance. Additionally, editorial reviews and testing updates, such as the inclusion of new multifunction options in expert comparisons, reflect the rapid pace of product iteration. Our report contextualizes these developments within long-term trends, distinguishing between short-term noise and structural shifts that should influence investment and product development decisions.
The Strategic Value of Comprehensive Market Intelligence
In a market growing at over 8 percent annually with evolving technological and regulatory requirements, generalized data is insufficient for high-stakes decision-making. PW Consulting's Worldwide Multifunction Baby Monitors Market report offers the depth and precision required to navigate this environment. We provide detailed segmentation analysis that goes beyond high-level totals, exploring the interplay between product types, distribution channels, and regional nuances. By accessing the full report, stakeholders gain visibility into specific market sizes, growth rates within segments, and competitive share dynamics that are not publicly disclosed.
The report is designed to support a range of strategic objectives. For investors, it provides validated market sizing and growth forecasts to assess opportunity size and risk. For manufacturers and brand managers, it offers competitive benchmarking and feature trend analysis to guide product roadmaps. For supply chain and procurement leaders, it highlights component market dynamics and regional supply considerations. The inclusion of detailed company profiles allows for direct comparison of strategies among key players, while the analysis of recent developments ensures that strategic plans are grounded in the current reality of the market.
Worldwide Multifunction Baby Monitors Market
Furthermore, our research addresses the operational implications of market entry or expansion. Understanding distribution channel efficacy, consumer preferences in different regions, and the regulatory hurdles specific to infant electronics is crucial for successful execution. The report synthesizes these elements into actionable insights, reducing the uncertainty associated with strategic planning. We invite executives and analysts to leverage this intelligence to secure a competitive advantage. The full dataset, including granular segmentation splits, detailed company assessments, and forward-looking scenario analyses, is available through our comprehensive publication. Accessing this complete intelligence will empower your organization to anticipate market shifts, optimize product offerings, and capture value in the evolving landscape of worldwide multifunction baby monitors.
For detailed analysis of this topic, please visit the official page: Worldwide Multifunction Baby Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com